House Rent Allowance (HRA) is a significant component of a salaried individual’s income, providing tax benefits under certain conditions. However, navigating HRA exemptions can sometimes be challenging. Let’s delve into common problems and solutions related to HRA in income tax.
What is House Rent Allowance (HRA)?
HRA is a part of the salary provided by employers to employees to cover rental expenses. It is partially exempt from taxes under Section 10(13A) of the Income Tax Act, 1961. The exemption is calculated based on the least of the following three amounts:
- Actual HRA received.
- Metro Cities: For those living in metro cities (Delhi, Mumbai, Kolkata, Chennai), the HRA exemption is calculated as 50% of the basic salary plus dearness allowance.
- Non-Metro Cities: For those living in non-metro cities, the HRA exemption is calculated as 40% of the basic salary plus dearness allowance.
- Actual Rent Paid: The actual rent paid minus 10% of the basic salary plus dearness allowance is also considered in the calculation.
Recent Changes in HRA Rules
There haven’t been any significant recent changes specifically to House Rent Allowance (HRA) rules in India. However, here are some key points and updates to keep in mind:
- Old vs. New Tax Regime:
- Under the new tax regime introduced in 2020, HRA exemptions are not available. Taxpayers need to choose between the old and new regimes based on their overall tax liability.
- Metro City Status:
- There have been discussions about including Bengaluru as a metro city for HRA purposes, which would allow taxpayers to claim a 50% exemption on salary equivalent to HRA. However, this change has not been implemented yet.
- Income Tax Slabs and Exemptions:
- The income tax slabs have been reduced from six to five, and the basic exemption limit has been increased to ₹3 lakh. The new tax regime is the default regime from the assessment year 2024-25 onwards.
- Documentation Requirements:
- The requirement for the landlord’s PAN if the annual rent exceeds ₹1 lakh remains unchanged. Proper documentation, including rent receipts and rental agreements, is essential for claiming HRA exemption.
What if Landlord Refuses to Provide a PAN
If your landlord refuses to provide their PAN, you can still claim HRA exemption, but there are a few steps you should follow:
- Declaration:
- You can submit a declaration from your landlord stating that they do not have a PAN. This declaration should include the landlord’s name, address, and the amount of rent paid.
- Alternative Documentation:
- Keep all rent receipts and a copy of the rental agreement as proof of rent payments. These documents can support your claim for HRA exemption.
- Form 60:
- If the landlord does not have a PAN, they can fill out Form 60, which is a declaration form for individuals who do not have a PAN but are entering into financial transactions.
- Consult Your Employer:
- Inform your employer about the situation. They may have specific guidelines or additional documentation requirements to process your HRA claim without the landlord’s PAN.
- Income Tax Department:
- If needed, you can also consult with the Income Tax Department or a tax professional for further guidance on how to handle this situation.
It’s important to maintain transparency and proper documentation to avoid any issues during tax assessments.
Top Mistakes to Avoid When Claiming HRA Exemption
Claiming House Rent Allowance (HRA) exemption can significantly reduce your taxable income, but it’s essential to avoid common mistakes to ensure you get the full benefit. Here are the top mistakes to avoid:
1. Incorrect Calculation of HRA Exemption
- Mistake: Misunderstanding the formula for HRA exemption.
- Solution: Use the correct formula: the least of actual HRA received, 50% of salary (metro cities) or 40% of salary (non-metro cities), or rent paid minus 10% of salary.
2. Inadequate Documentation
- Mistake: Failing to provide necessary documents like rent receipts and rental agreements.
- Solution: Keep all rent receipts, a copy of the rental agreement, and if the annual rent exceeds ₹1 lakh, the landlord’s PAN.
3. Claiming HRA for Self-Owned Property
- Mistake: Attempting to claim HRA while living in a self-owned property.
- Solution: HRA can only be claimed if you are living in a rented house and paying rent.
4. Not Informing Employer About Rent Changes
- Mistake: Not updating your employer about changes in rent amount or rental address.
- Solution: Inform your employer promptly about any changes to ensure accurate HRA calculation.
5. Ignoring the New Tax Regime
- Mistake: Not considering the impact of the new tax regime, which does not allow HRA exemptions.
- Solution: Evaluate both the old and new tax regimes to determine which is more beneficial for your overall tax liability.
6. Not Maintaining Bank Statements
- Mistake: Paying rent in cash without maintaining bank statements.
- Solution: Pay rent through bank transfers or cheques to maintain a clear record of transactions.
7. Incorrect Rent Receipts
- Mistake: Submitting rent receipts that lack essential details like the landlord’s signature or the correct rent amount.
- Solution: Ensure rent receipts are properly filled out with all necessary details.
8. Not Claiming HRA for Rent Paid to Family Members
- Mistake: Assuming you cannot claim HRA for rent paid to parents or other family members.
- Solution: You can claim HRA for rent paid to family members, provided you have a valid rental agreement and rent receipts. Ensure the family member declares this rental income in their tax returns.
9. Overlooking Rent Paid in Different Cities
- Mistake: Not considering rent paid in different cities if you have relocated during the year.
- Solution: Calculate HRA exemption separately for each city if you have moved during the financial year.
10. Not Consulting a Tax Professional
- Mistake: Trying to navigate HRA exemptions without professional advice.
- Solution: Consult a tax professional to ensure accurate calculations and compliance with tax laws.
By avoiding these common mistakes, you can maximize your HRA benefits and ensure a smooth tax filing process.
Conclusion
Navigating HRA exemptions can be complex, but understanding the rules and maintaining proper documentation can help maximize your tax benefits. Always stay informed about the latest tax regulations and consult with a tax professional if needed.
Frequently Asked Questions
1. What is House Rent Allowance (HRA)?
HRA is a component of a salary provided by employers to employees to cover rental expenses. It is partially exempt from taxes under Section 10(13A) of the Income Tax Act, 1961.
2. How is HRA exemption calculated?
The HRA exemption is calculated based on the least of the following three amounts:
- Actual HRA received.
- 50% of salary (for those living in metro cities) or 40% of salary (for non-metro cities).
- Rent paid minus 10% of salary.
3. Can I claim HRA if I live in my own house?
No, HRA exemption can only be claimed if you are living in a rented house and paying rent.
4. What documents are required to claim HRA exemption?
You need to provide rent receipts and, if the annual rent exceeds ₹1 lakh, the landlord’s PAN. A rental agreement and bank statements showing rent payments can also support your claim.
5. What if my landlord does not have a PAN?
If your landlord does not have a PAN, they can provide a declaration stating that they do not have one. Alternatively, they can fill out Form 60.
6. Can I claim HRA if my landlord lives abroad?
Yes, you can claim HRA even if your landlord lives abroad. Ensure you have proper documentation like rent receipts, rental agreement, and bank statements showing rent payments.
7. What happens if I switch between the old and new tax regimes?
Under the new tax regime introduced in 2020, HRA exemptions are not available. You need to choose between the old and new regimes based on your overall tax liability.
8. How do I prove rent payments without a PAN card from the landlord?
You can prove rent payments with rent receipts, a rental agreement, bank statements, and a declaration from the landlord stating they do not have a PAN.
9. Can I claim HRA for rent paid to my parents?
Yes, you can claim HRA for rent paid to your parents, provided you have a valid rental agreement and rent receipts. Your parents must declare this rental income in their tax returns.
10. What are the common mistakes to avoid when claiming HRA?
Common mistakes include incorrect calculation of HRA exemption, missing documentation, claiming HRA for self-owned property, and not understanding the differences between the old and new tax regimes.
-
Home Loan Rates in October 2026: Should You Lock Your Interest Rate Now or Wait for the RBI Decision?
Home Loan Rates in October 2026: Lock Your Interest Rate Now or Wait for the RBI Decision on 7 October? Home LoansRBI PolicyOctober 2026 Home Loan Rates in October 2026: Should You Lock Your Interest Rate Now or Wait for the RBI Decision? Listed home loan rates start near 7.10% while the Monetary Policy Committee…
-
RBI October 2026 Rate Hike Could Make Home Loans Costlier: What Borrowers Should Do Before Their Next EMI Reset
RBI October 2026 Policy: Possible Repo Rate Hike and What It Means for Your Home Loan EMI Reset Personal Finance · Home Loans · RBI Policy Watch RBI October 2026 Rate Hike Could Make Home Loans Costlier: What Borrowers Should Do Before Their Next EMI Reset The Monetary Policy Committee announces its decision on 7…
-
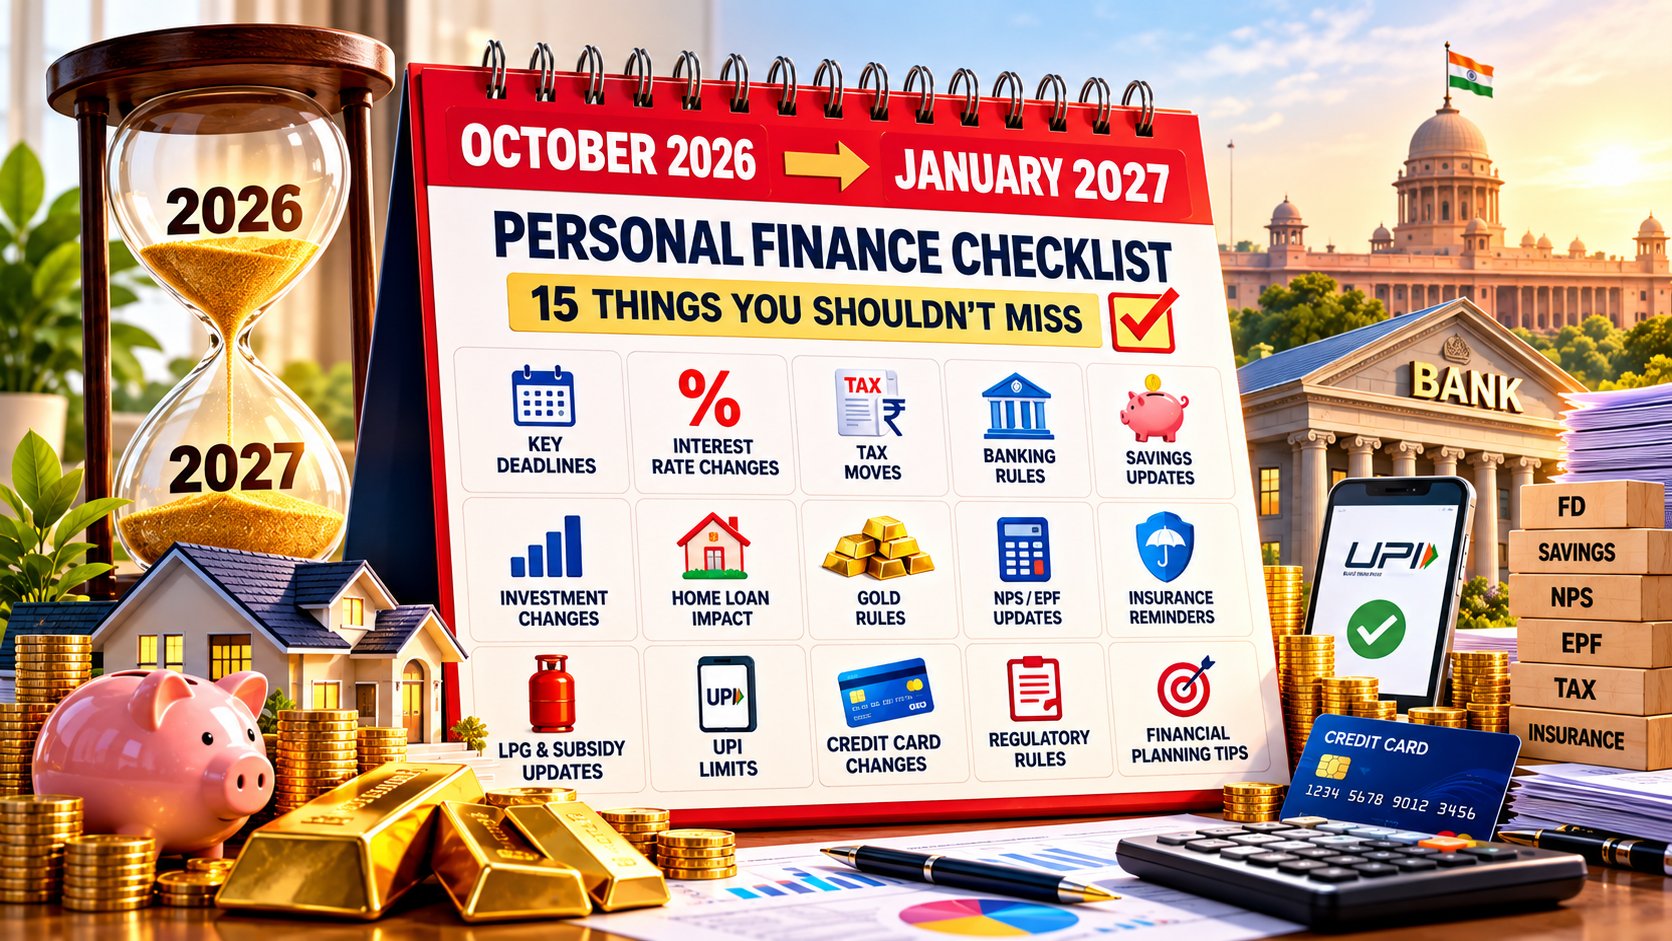
October 2026 to January 2027 Personal Finance Checklist: 15 Deadlines, Interest-Rate Changes, Tax Moves and Banking Rules You Shouldn’t Miss
October 2026 to January 2027 Personal Finance Checklist: 15 Deadlines, Rate Changes and Banking Rules Personal Finance · Tax, Banking and Rates · India, Q3 and Q4 FY 2026-27 October 2026 to January 2027 Personal Finance Checklist: 15 Deadlines, Interest-Rate Changes, Tax Moves and Banking Rules You Shouldn’t Miss Two RBI policy meetings, an extended…
-
Gold Loans Up 83% as Credit Card Dues Grow Just 3.6%: What India’s 2026 Debt Shift Says About Household Finances
Gold Loans Up 83% as Credit Card Dues Grow 3.6%: India’s 2026 Household Debt Shift Explained Personal Finance · RBI Credit Data · India, August 2026 Gold Loans Up 83% as Credit Card Dues Grow Just 3.6%: What India’s 2026 Debt Shift Says About Household Finances RBI sectoral data for August 2026 shows bank loans…
-
NPS Charges Change From October 2026 — Why a 0.20% Yearly Fee on Your Whole Corpus Matters Before You Contribute More
NPS PoP Charges From October 1, 2026: How the New 0.20% Yearly Fee Affects Your Retirement Corpus Retirement · NPS · India, from October 1, 2026 NPS Charges Change From October 2026 — Why a 0.20% Yearly Fee on Your Whole Corpus Matters Before You Contribute More A PFRDA circular dated August 28, 2026 replaces…
-
Four Sovereign Gold Bond Tranches Open for Early Exit in October 2026 — Should You Redeem, Hold to Maturity or Move Your Money?
SGB Premature Redemption October 2026: Four Tranches Can Exit Early — Redeem, Hold or Switch? Personal Finance · Gold Investing · India, October 2026 Four Sovereign Gold Bond Tranches Open for Early Exit in October 2026 — Should You Redeem, Hold to Maturity or Move Your Money? SGB 2019-20 Series V and VI and 2020-21…
-
EPF Pension Rule Changed in 2026: Who Now Gets EPS Coverage Under the ₹25,000 Wage Ceiling and What It Means for Retirement
EPS Wage Ceiling Raised to ₹25,000 in 2026: Who Now Gets Pension Coverage and How Retirement Changes EPFO Update Pension Retirement EPF Pension Rule Changed in 2026: Who Now Gets EPS Coverage Under the ₹25,000 Wage Ceiling and What It Means for Retirement The EPFO wage ceiling rose from ₹15,000 to ₹25,000 a month from…
-
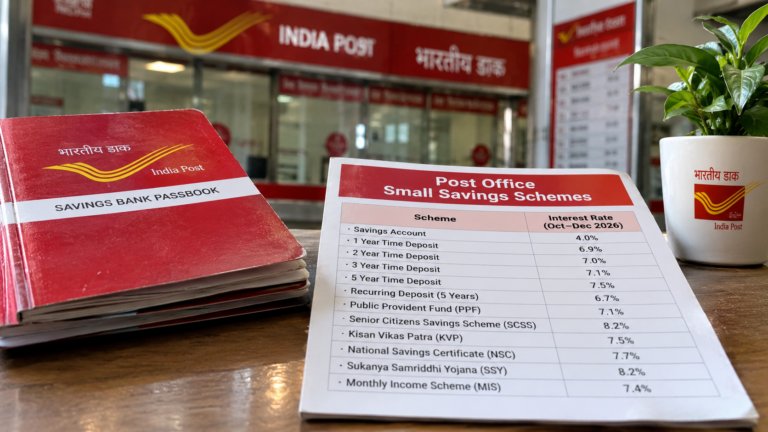
RBI Rate Hike in October 2026? What a Higher Repo Rate Could Mean for Your Home Loan EMI, FD Returns and Savings
RBI Rate Hike in October 2026? What a 5.50% Repo Rate Could Mean for Your Home Loan EMI, FD Returns and Savings RBI Policy Home Loans Fixed Deposits RBI Rate Hike in October 2026? What a Higher Repo Rate Could Mean for Your Home Loan EMI, FD Returns and Savings The repo rate stands at…
-
EPF Claim Forms and Their Uses in 2026: Which Form Actually Gets Your PF Money Out
EPF Claim Forms and Their Uses in 2026: Which Form Fits Your PF Withdrawal Personal Finance · EPF · Updated 30 September 2026 EPF Claim Forms and Their Uses in 2026: Which Form Actually Gets Your PF Money Out Form 19, Form 31, Form 10C, Form 13, Form 20 and the new Form 121 each…
-

BSE Sensex and NSE Nifty 50 Today: Nifty Touches Its 200-Week Average as September Turns Ugly, So What Happens on 30 September 2026?
BSE Sensex and NSE Nifty 50 Today: Nifty Touches Its 200-Week Average as September Turns Ugly, So What Happens on 30 September 2026? Quick Summary: Market Close, 29 September 2026 BSE Sensex: 72,529.07, down 242.65 points or 0.33 percent NSE Nifty 50: 22,716.20, down 64.05 points or 0.28 percent Nifty Bank: 54,259.95, down 0.39 percent…