Retirement · National Pension System · PFRDA Framework · India 2026
NPS Schemes Are Being Regrouped and Renamed: What the New A-to-E Risk Framework Changes Before You Pick a Pension Fund
PFRDA has standardised how every NPS scheme is classified, named, displayed and compared. Schemes now sit in five broad categories, funds designed under the Multiple Scheme Framework carry a risk label from A to E based on equity mandate, and the distinction between Common Schemes and MSF schemes has been discontinued.
For most of its life, NPS asked you a single question at sign-up: auto or active. That question is now the wrong starting point. The system has quietly grown into a marketplace of differentiated funds, some of them able to hold as much equity as a mid-cap mutual fund, and the regulator has just imposed a filing system on it. The order in which you make decisions has changed, and so has the name printed on the scheme you already own.
Table of Contents
Quick Summary
PFRDA’s circular of 28 August 2026 sorts every NPS scheme into five categories: Lifecycle-based, Active Choice, NPS Sanchay, MSF and Regulation 4A schemes. Funds built under the Multiple Scheme Framework get a risk label from A to E, set purely by the equity allocation mandate, running from 80 to 100 per cent equity at A down to 0 to 10 per cent at E. Each pension fund may offer at most two schemes per category per Tier. Subscribers now pick the strategy and risk band first, then compare pension funds within it.
What We Know
The framework arrived as a pair of circulars issued on the same day. One prescribes the classification and presentation rules, the other tells pension funds how quickly to comply. These are the confirmed elements.
- The framework is prescribed through Circular No. PFRDA/2026/47/REG-PF/10 dated 28 August 2026, with the operational directions in Circular No. PFRDA/2026/48/REG-PF/11 of the same date.
- It supersedes the earlier MSF circular of 16 September 2025 and discontinues the distinction between Common Schemes and MSF schemes with effect from 28 August 2026.
- All NPS schemes are classified into Lifecycle-based Schemes, Active Choice, NPS Sanchay, MSF Schemes and Regulation 4A Schemes such as NPS Vatsalya, NPS Swasthya and NPS MSME.
- Every MSF scheme carries one of five category labels, A through E, assigned on its equity allocation mandate alone.
- Existing MSF schemes whose equity mandate straddles more than one band had to be restructured into a single category and renamed under the prescribed convention within 30 days of the circular.
- Where a pension fund had more than two schemes in one category, it must merge, subsume or restructure them within 45 days.
- Every MSF scheme needs prior PFRDA approval, must display a Riskometer and must maintain a standardised NPS Scheme Essentials document.
- Before a subscriber selects a pension fund, the platform must display scheme name, fund name, launch date, historical returns, benchmark and comparative benchmark returns, charges, Riskometer and assets under management.
- A subscriber may hold only one of Lifecycle-based or Active Choice at a time under the same account, but may hold more than one MSF scheme simultaneously.
- A maximum of two change requests per account per financial year are allowed for pension fund, scheme, or any combination of the two.
- The framework does not apply to accounts tagged to the Government sector.
From Two Options to a Marketplace: Why the Cleanup Became Unavoidable
NPS began as a deliberately simple retirement product. You chose auto or active, and within active you split money across equity, corporate debt and government securities. Simplicity was the feature. Comparison was easy because there was almost nothing to compare.
That changed on 1 October 2025, when PFRDA launched the Multiple Scheme Framework for non-government subscribers. Pension funds could suddenly design differentiated schemes aimed at specific groups such as gig workers, self-employed professionals and corporate employees, hold them across central recordkeeping agencies under a single PAN, and offer equity allocation as high as 100 per cent in high-risk variants. Add NPS Vatsalya for minors, NPS Swasthya, NPS MSME and the composite NPS Sanchay for informal-sector savers, and the product shelf expanded faster than the language used to describe it.
The result was a familiar problem in Indian financial products. Schemes with genuinely different risk profiles sat under one roof with names that gave no clue about what was inside them, returns quoted against inconsistent benchmarks, and risk disclosed differently by each fund. Comparison became guesswork. The new framework is an attempt to fix the labelling before the shelf gets any longer.
One Banner, Five Buckets: The New Map of Every NPS Scheme
The first thing the framework does is decide which shelf a scheme belongs on. These five buckets now cover everything a non-government subscriber can be sold, and the differences between them are about who decides the asset mix, not about which fund house is better.
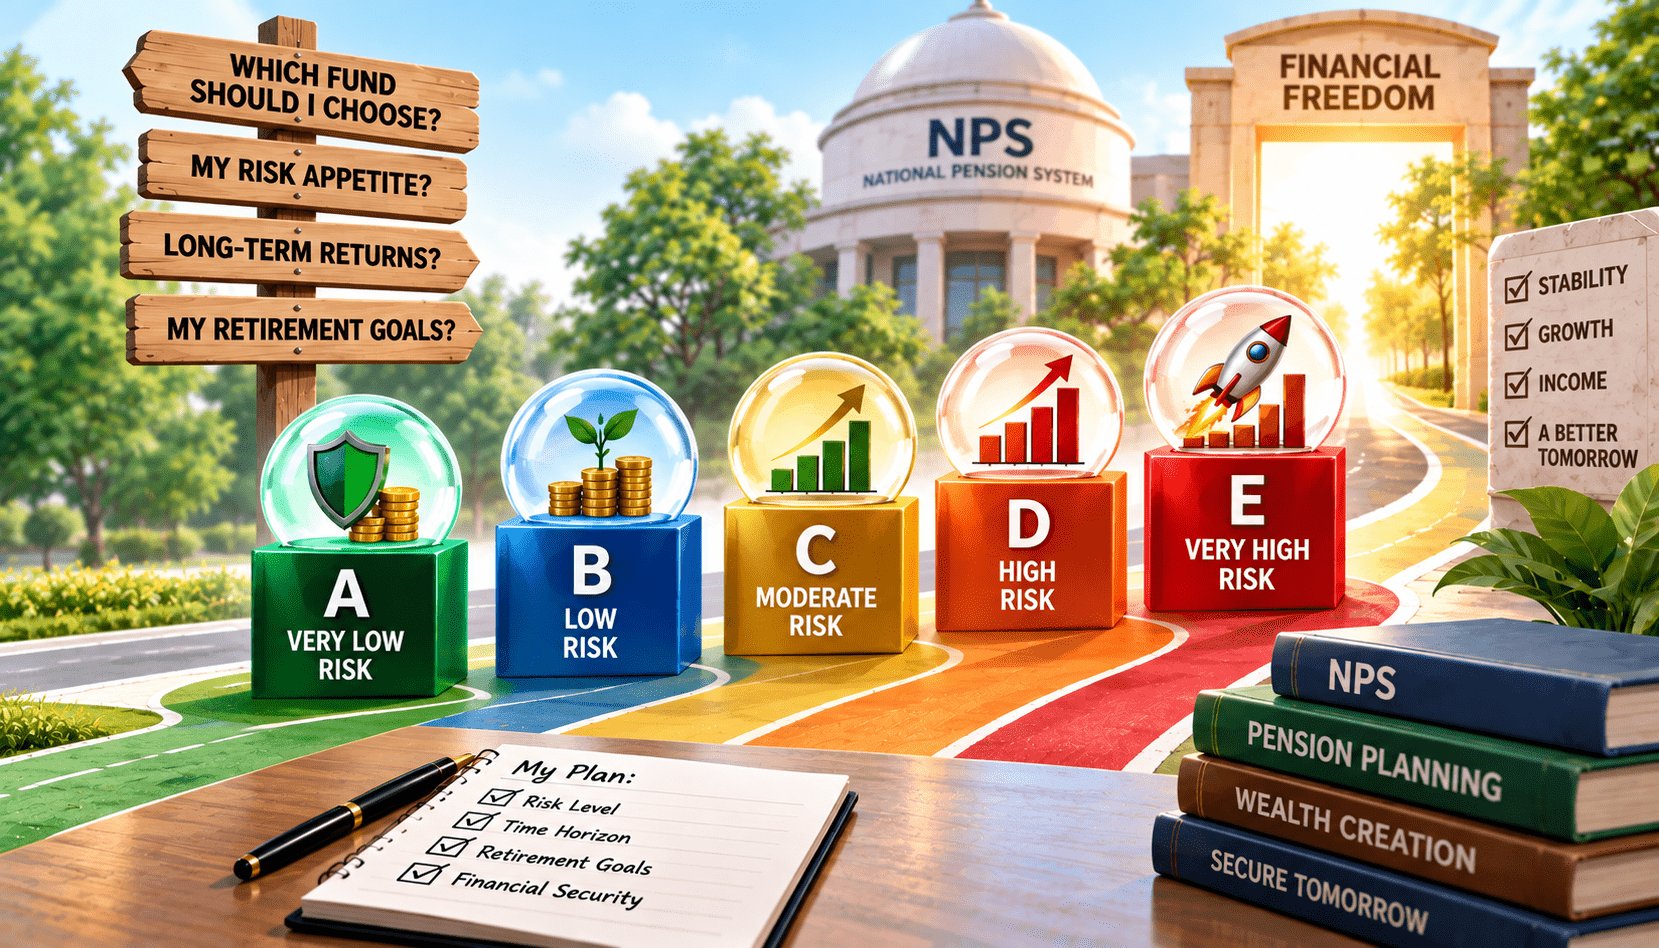
A to E: How One Number Now Decides a Scheme’s Risk Label
This is the sharpest change in the document. Every MSF scheme is classified into one of five categories based on its equity allocation mandate, and nothing else. Not the fund’s internal view of risk, not its marketing description, not its past volatility. The mandate range decides the letter, and the letter has to appear in the name.
0–10%
10–35%
35–60%
60–80%
80–100%
The naming convention, decoded
Every MSF scheme name now follows a fixed structure: the pension fund’s abbreviation, then NPS, then the MSF category code, then the scheme name. Tier II schemes append Tier 2 at the end. The practical effect is that the risk band travels with the product everywhere it is quoted, so a statement, a comparison table or a sales pitch all carry the same letter. You should no longer need to open a factsheet to learn how much equity a scheme is allowed to hold.
Ten Things That Change: The Before and After, Line by Line
The circular touches structure, naming, disclosure, comparison and the selection journey itself. Read down the middle column to see what a subscriber actually gains.
| Area | Earlier framework | New framework | What the subscriber gains |
|---|---|---|---|
| Overall structure | Common Schemes and MSF had separate structures | The distinction is removed entirely | One unified NPS architecture to learn |
| Scheme classification | Schemes could carry different structures and mandates | Organised under standard categories | Clear view of what strategy is being bought |
| MSF risk categories | No common risk classification across offerings | Five labels, A to E, set by equity exposure | Risk identifiable before investing |
| Scheme naming | Names varied widely across pension funds | Fund abbreviation, NPS, category code, scheme name | Recognition and like-for-like comparison |
| How you choose | Often started with a fund house or a return chart | Select scheme type and risk category, then compare funds | Asset allocation decided before fund selection |
| Scheme comparison | Information presented inconsistently | Returns, benchmark, charges, Riskometer and AUM shown together | Apples-to-apples comparison |
| Holding multiple schemes | Architecture was relatively restrictive | More than one MSF scheme can be held at once | Diversification inside NPS itself |
| Scheme disclosure | Information spread across documents | A standard NPS Scheme Essentials document | The key facts in one place |
| Risk disclosure | No single uniform risk presentation | Riskometer mandatory on MSF schemes | Risk read alongside returns, not after them |
| Benchmarking | Comparisons could be inconsistent | Schemes evaluated against relevant benchmarks | Fund manager performance judged fairly |
The Selection Journey Has Been Reversed, and That Is the Real Reform
Under the old habit, a subscriber opened an app, looked at a table of pension fund returns, picked whoever was on top of the one-year column, and only then discovered what asset mix they had bought. The framework inverts this. You first choose the scheme type and, within MSF, the risk category. Only then does the platform show you the pension funds competing inside that box, side by side, with the same fields for each.
This is the same logic that reshaped mutual fund selection after category rationalisation. Once every fund in a box has to follow the same mandate, the comparison stops being about who took more risk and starts being about who managed the same risk better. It is a smaller change on paper than the A-to-E labels, and a larger one in practice.
Rules Worth Knowing Before You Move Anything
Several operating rules sit quietly in the circular and matter more than the headline categories once you start switching.
The switching limit most people miss
You can submit a maximum of two change requests per account per financial year, covering a change of pension fund, a change of investment scheme, or any combination of the two. That is a budget, not a formality. If you use both requests chasing a good quarter in March, you have nothing left if your circumstances change in the same year. Treat a switch as a considered decision about strategy, not a reaction to a league table.
What happens if a scheme is wound up
If an MSF scheme is wound up, subscribers are given the option to select a new scheme. If no choice is exercised, the investment is migrated automatically to the Life Cycle 50 Moderate variant of the same pension fund under Tier I. That default is deliberately middle-of-the-road, which means an aggressive investor who ignores the notice could find their allocation cut roughly in half without doing anything.
What happens when you merge schemes
Where a subscriber holds multiple schemes, one can be merged into another target scheme. After the merger, the rules, limits and vesting period of the target scheme govern the consolidated investment. The merged money takes on the destination’s conditions, not its own history, which is worth checking before consolidating a long-held account into a newer one.
Two things the framework leaves alone
The rules do not apply to accounts tagged to the Government sector, so central and state government subscribers continue under their existing arrangements. And value-added services that pension funds may now offer, such as income payout solutions, annuity-related services and succession planning, are explicitly barred from changing the investment objective or risk profile of the underlying scheme.
What Is Still Unclear
Several practical questions were not settled in the public circulars as of 19 September 2026, and subscribers planning a switch should treat them as open.
- Whether all pension funds completed the renaming and reclassification within the 30-day window, and how the revised names will surface in older statements and third-party apps.
- How the Riskometer for an MSF scheme will be calculated and how frequently it will be refreshed, given the category itself is fixed by mandate.
- Which benchmarks will be prescribed as the relevant comparator for each category, and whether comparative benchmark returns will be uniform across pension funds.
- How schemes that are merged or restructured will report historical returns, and whether the track record of the merged scheme or the target scheme is carried forward.
- Whether the government sector will eventually be brought under the same classification, or continue on a separate track.
- How quickly the standardised display of returns, charges, Riskometer and AUM will appear consistently across every CRA and distributor platform.
A Short Checklist Before Your Next NPS Decision
Frequently Asked Questions
What are the new NPS scheme categories introduced by PFRDA?
All NPS schemes are now classified into five categories: Lifecycle-based Schemes, where equity allocation changes automatically with age; Active Choice, where the subscriber sets the asset mix; NPS Sanchay, a composite scheme for informal-sector subscribers; MSF schemes designed by pension funds and labelled by equity exposure; and Regulation 4A schemes such as NPS Vatsalya, NPS Swasthya and NPS MSME.
What do the A, B, C, D and E risk labels mean in NPS?
They are MSF risk categories set purely by a scheme’s equity allocation mandate. Category A is Aggressive Growth at 80 to 100 per cent equity, B is High Growth at 60 to 80 per cent, C is Balanced Growth at 35 to 60 per cent, D is Conservative at 10 to 35 per cent, and E is a debt category holding 0 to 10 per cent equity with the rest in government and corporate bonds.
Will my existing NPS scheme name change?
If you hold an MSF scheme, very likely yes. Pension funds were given 30 days from 28 August 2026 to rename existing MSF schemes under the prescribed convention, which is the fund abbreviation, then NPS, then the category code, then the scheme name, with Tier 2 appended for Tier II schemes. Your investment and units are unaffected by a renaming.
Can I hold more than one NPS scheme at the same time?
Yes, but with a condition. You may hold investments in more than one MSF scheme simultaneously. You may hold only one of Lifecycle-based or Active Choice at a time under the same account. A subscriber can have multiple accounts under one PRAN, and each account carries one scheme.
How many times can I change my NPS pension fund or scheme in a year?
A maximum of two requests per account per financial year, covering a change of pension fund, a change of investment scheme, or any combination of the two. Because the limit is shared between both types of change, it is worth deciding the strategy and the fund together rather than switching one and then the other.
Does the new NPS framework apply to government employees?
No. The circular states that the framework does not apply to accounts tagged to the Government sector. Central and state government subscribers continue under their existing arrangements. The classification, naming and MSF risk labels are aimed at the non-government segment, which includes corporate employees, self-employed professionals and all-citizen subscribers.
What happens to my money if an NPS scheme is wound up?
Subscribers are given the option to select a new scheme. If no choice is made, the investment migrates automatically to the Life Cycle 50 Moderate variant of the same pension fund under Tier I. That is a middle-risk default, so an investor who wanted high equity exposure should respond to the notice rather than let the migration happen by silence.
How should I choose an NPS scheme under the new framework?
Work in the order the framework now assumes. Decide the scheme type first, then the risk category that matches your years to retirement and tolerance for drawdowns, and only then compare pension funds inside that category using the standardised display of returns, benchmark, charges, Riskometer and AUM. Comparing a Category B fund with a Category D fund tells you about equity exposure, not about manager skill.
The Short Version
PFRDA has given NPS a filing system. Five categories cover every scheme, MSF funds carry a risk letter from A to E fixed by their equity mandate, names now state the category, and every pension fund must present returns, benchmarks, charges, risk and AUM in the same format. The distinction between Common Schemes and MSF schemes is gone, each fund is capped at two schemes per category per Tier, and the selection journey now runs strategy first, fund manager second. Nothing about your existing contributions or units changes. What changes is how readable the shelf is, and how little excuse there now is for buying risk you did not intend.