Sovereign Gold Bond Investors Have a New Exit Window in October 2026: Should You Redeem, Hold or Move Your Money Elsewhere?
- EPFO Update
- Pension
- Retirement
EPF Pension Rule Changed in 2026: Who Now Gets EPS Coverage Under the ₹25,000 Wage Ceiling and What It Means for Retirement
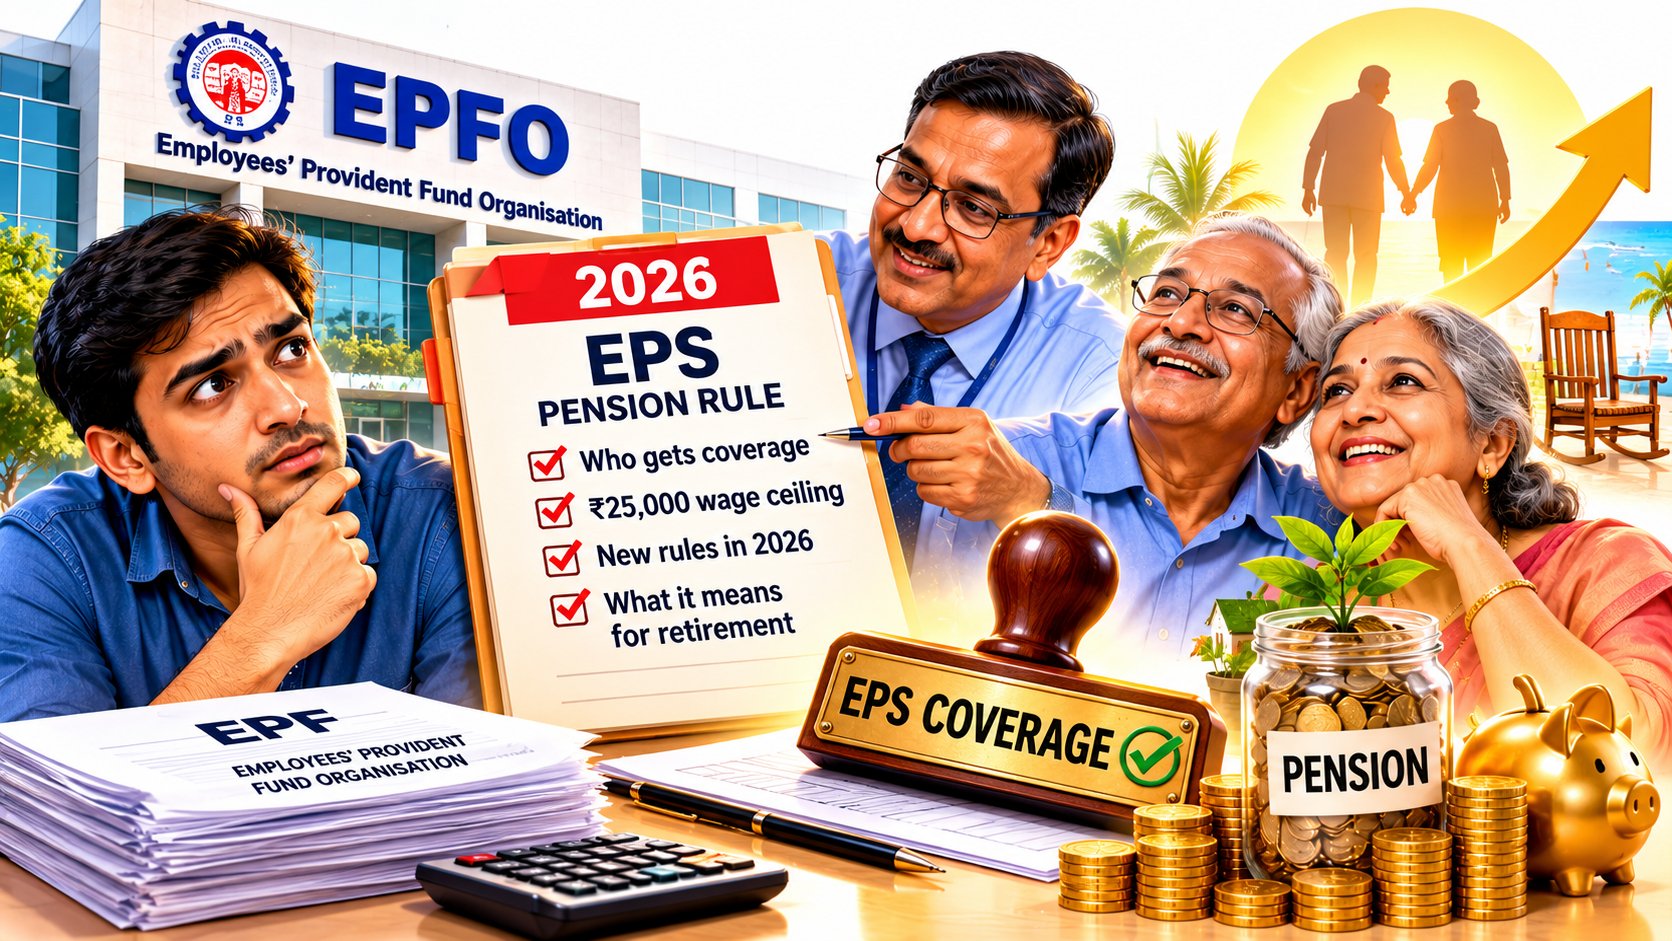
The EPFO wage ceiling rose from ₹15,000 to ₹25,000 a month from September 17, 2026. A follow-up amendment to the Employees’ Pension Scheme brings EPF members earning up to ₹25,000 into pension cover automatically.
For twelve years, a quiet line at ₹15,000 decided whether a salaried worker in India would retire with a monthly EPS pension or only a provident fund lump sum. Many people who joined the workforce after 2014 on salaries just above that line never got pension cover at all, often without realising it. In September 2026 that line moved to ₹25,000. Here is who crosses into the pension net, what it costs in your pay slip, and how much monthly income it could add when you retire.
The Two-Minute Briefing
What We Know
- The Cabinet approved the change on September 16, 2026, and the gazette notification S.O. 5109(E) followed on September 17.
- The wage ceiling for EPF, EPS and EDLI is now ₹25,000 a month, effective September 17, 2026.
- An EPS amendment notified on September 25, 2026 applies from September 17 and auto-enrols EPF members earning up to ₹25,000 who were outside EPS.
- Enrolment is the employer’s statutory duty; members do not need to apply.
- The employee share stays at 12%, and 8.33% of wages (up to the ceiling) from the employer’s share goes to EPS.
What Is Still Unclear
- Reports differ on whether the government’s 1.16% EPS subsidy is now calculated on ₹25,000 or remains capped at ₹15,000.
- Detailed EPFO guidance on pension calculation for members whose service spans both ceilings is still emerging.
- Exactly how voluntary EPS enrolment will work for those earning above ₹25,000 has not been fully spelt out.
- The EDLI maximum benefit stays at ₹7 lakh for now, subject to a future actuarial review.
- No revision to the minimum EPS pension has been announced alongside this change.
How a 2014 Line in the Sand Left Lakhs Without a Pension
In September 2014, the ceiling was raised from ₹6,500 to ₹15,000, and a related rule change meant that people joining EPF after that date with wages above ₹15,000 were not eligible for EPS. They still built a provident fund, but their employer’s full 12% went into the PF account rather than partly into a pension fund.
As salaries rose over the next decade, more and more entry-level and mid-level workers found themselves on the wrong side of that ₹15,000 line. The 2026 amendment closes that gap for anyone earning up to ₹25,000.
- September 2014Wage ceiling set at ₹15,000. New members earning above it are left outside EPS.
- September 16, 2026Union Cabinet approves raising the ceiling to ₹25,000.
- September 17, 2026Gazette notification S.O. 5109(E) published. The new ceiling takes effect the same day.
- September 25, 2026EPS amendment notified under the Code on Social Security, 2020, applying from September 17.
- September 2026 payrollEmployers split contributions: old ceiling for September 1 to 16, new ceiling for September 17 to 30.
- October 2026 onwardsFirst full month on the new ceiling. Employers may recover deferred employee shares from September.
Are You Inside the New Pension Net? Three Real-World Profiles
Earning ₹15,001 to ₹25,000, joined after 2014
This is the group the amendment targets most directly. If you were an EPF member without EPS, your employer must now enrol you. Your pension service starts counting from September 17, 2026.
Already in EPS, earning above ₹15,000
You keep your existing pension service. From September 17, 2026, the employer’s EPS contribution is calculated on wages up to ₹25,000 instead of ₹15,000, so future service counts at a higher pensionable salary.
Earning above ₹25,000 and outside EPS
You are not brought in automatically. Reports on the amendment say voluntary enrolment may be possible, but detailed rules are still awaited.
Your pay slip or the EPFO member passbook shows whether any amount is going to “Pension Contribution” or “EPS”. If it showed zero before September 17, 2026 and your wages are up to ₹25,000, that line should start reflecting a contribution.
The Trade-Off Nobody Mentions: Less Lump Sum, More Lifelong Income
EPS coverage does not come from a new pocket. The employee still pays 12% into EPF. The change is in how the employer’s 12% is split. For someone who was outside EPS, all of it used to go to the PF account. Now 8.33% of wages goes into the pension fund and only the rest stays in PF.
| Monthly wage | Employee EPF (12%) | Employer to EPS (8.33%) | Employer to EPF | Earlier employer to EPF (no EPS) |
|---|---|---|---|---|
| ₹18,000 | ₹2,160 | ₹1,499 | ₹661 | ₹2,160 |
| ₹20,000 | ₹2,400 | ₹1,666 | ₹734 | ₹2,400 |
| ₹22,000 | ₹2,640 | ₹1,833 | ₹807 | ₹2,640 |
| ₹25,000 | ₹3,000 | ₹2,083 | ₹917 | ₹3,000 |
The PF account grows more slowly, but the money that moves to EPS buys something PF cannot: a monthly pension that is paid for life, with family pension benefits for a spouse and children under the scheme rules.
What happens to your take-home pay
If your PF was earlier calculated on ₹15,000 while you earned more, it is now calculated on actual wages up to ₹25,000. That raises the 12% employee deduction. On a ₹25,000 wage, it goes from ₹1,800 to ₹3,000, which is ₹1,200 less in hand each month. On a ₹20,000 wage, the deduction rises from ₹1,800 to ₹2,400. The money is not lost; it lands in your own PF account and earns the declared EPF interest rate.
EPFO guidance indicates that CTC is not the statutory basis for PF. An employer cannot simply cut your salary to absorb its higher contribution. If your gross pay changes, ask HR to explain how.
Doing the Pension Maths: What ₹25,000 Means in Rupees Later
EPS pension uses a fixed formula: pensionable salary × pensionable service ÷ 70. Pensionable salary is broadly the average of your last 60 months of wages, capped at the ceiling. A higher cap therefore lifts the maximum possible pension.
The catch for people already mid-career
The 30-year figure above only applies to someone whose entire career falls under the new cap. Reports on the amendment say pension is worked out pro rata for each ceiling period, so past service is not upgraded. The table below shows illustrative cases at constant wages.
| Profile | Service at ₹15,000 cap | Service after Sept 2026 | Wage counted after Sept 2026 | Illustrative monthly pension |
|---|---|---|---|---|
| Long-time EPS member, earns ₹25,000+ | 10 years | 20 years | ₹25,000 | ₹9,286 |
| Same member under old rules | 30 years | None | ₹15,000 | ₹6,429 |
| Newly enrolled worker on ₹20,000 | None | 25 years | ₹20,000 | ₹7,143 |
| Newly enrolled worker on ₹25,000 | None | 15 years | ₹25,000 | ₹5,357 |
For a newly covered worker, these are gains over zero: before the amendment, they were on track for no EPS pension at all. Actual pension depends on wage history, length of service and any future rule changes.
A monthly EPS pension generally needs at least 10 years of eligible service, with full pension from age 58. A newly enrolled worker who is 50 today would not reach 10 years of EPS service by 58 unless they keep working and contributing beyond that, so the benefit is much larger for younger workers.
Your Next Moves Before the October Salary Lands
A quick checklist for employees
- Compare your September and October pay slips for changes in the PF deduction.
- Log in to the EPFO member portal and check whether an EPS contribution now appears in your passbook.
- Make sure your UAN is linked to Aadhaar and your bank account, and that your date of birth matches, so pension records stay clean.
- Update your nomination, since EPS family pension depends on it.
- If you earn up to ₹25,000 and see no EPS credit after October, raise it with HR first, then through the EPFO grievance portal.
Questions worth asking HR
- Has my EPS enrolment been done from September 17, 2026?
- Is my PF now calculated on actual wages up to ₹25,000?
- Will any deferred employee share for September be recovered in October?
Questions People Are Searching Right Now
What is the new EPF and EPS wage ceiling in 2026?
The wage ceiling was raised from ₹15,000 to ₹25,000 per month, effective September 17, 2026, through notification S.O. 5109(E). It was the first revision since September 2014.
Who gets EPS pension coverage under the new rule?
EPF members earning up to ₹25,000 a month who were not part of EPS are to be enrolled automatically, along with new joiners in that wage range. This mainly covers workers earning between ₹15,000 and ₹25,000 who were left out after the 2014 changes.
Do I need to apply to join EPS after the wage ceiling hike?
No application is required from members. Enrolling eligible employees is the employer’s statutory responsibility under the amendment notified on September 25, 2026.
How much does the employer contribute to EPS now?
The employer’s 8.33% share on wages up to ₹25,000 goes to EPS. At the full ceiling, that is ₹2,083 a month, up from ₹1,250 on the old ₹15,000 ceiling. The rest of the employer’s 12% goes to your EPF account.
Will my take-home salary fall because of the new wage ceiling?
It can, if your PF was earlier calculated on ₹15,000 and is now calculated on higher actual wages up to ₹25,000. On ₹25,000, the employee deduction rises from ₹1,800 to ₹3,000 a month. That money goes into your own PF account.
How is EPS pension calculated after the ceiling change?
The formula is pensionable salary multiplied by pensionable service, divided by 70. Reports on the amendment say pension is worked out pro rata for each ceiling period, so service before September 17, 2026 counts at the ₹15,000 cap and later service at up to ₹25,000.
Will my existing pension service be recalculated at ₹25,000?
According to reports on the amendment, no. Past service stays linked to the ceiling that applied at the time. Only service from September 17, 2026 onwards counts at the higher limit.
How many years of service do I need to get an EPS pension?
A monthly EPS pension generally requires at least 10 years of eligible service, with full pension from age 58. Members who leave with less than 10 years can usually withdraw their EPS benefit instead.