How EPFO’s new 2025 EPS correction rules are reshaping pension security in India. From fixing hidden contribution errors to unlocking faster, digital-age claim approvals—this surprising reform could mean thousands more in your retirement payout. Find out what changes most employees don’t even know about yet.
The Employees’ Provident Fund Organisation (EPFO) released guidelines on December 19, 2025, to fix errors in Employees’ Pension Scheme (EPS) contributions. These rules standardize corrections across offices, tackling delays in pension processing caused by employer mistakes.
Table of Contents
Why Errors Disrupt Pensions
EPS contribution errors create inaccurate pension records that block or delay retirement claims. Employers often wrongly enrol ineligible workers or skip eligible ones, leading to mismatched service history and fund allocations.
Types of Errors
Two main issues plague EPS records. Employers deposit contributions for ineligible employees—like those earning over ₹15,000 monthly post-2014 or non-employees such as directors—crediting pension accounts wrongly.
Eligible workers miss out when employers divert full shares to PF instead of splitting for EPS, erasing pensionable service and non-contributory periods.
Processing Delays
Field offices handled cases inconsistently before the December 2025 circular, causing months-long backlogs. Claims stall during verification of pensionable service, wage calculations, and fund transfers.
EPFO auto-rejects Form 10D for mismatches in dates, service, or KYC, pushing approvals by 3-12 months and sparking disputes.
Benefit Reductions
Wrong entries shrink monthly pensions—missing five years of service cuts ₹500-₹900. Zero EPS wages break formulas; inflated service for ineligible members triggers refunds with interest, complicating settlements.
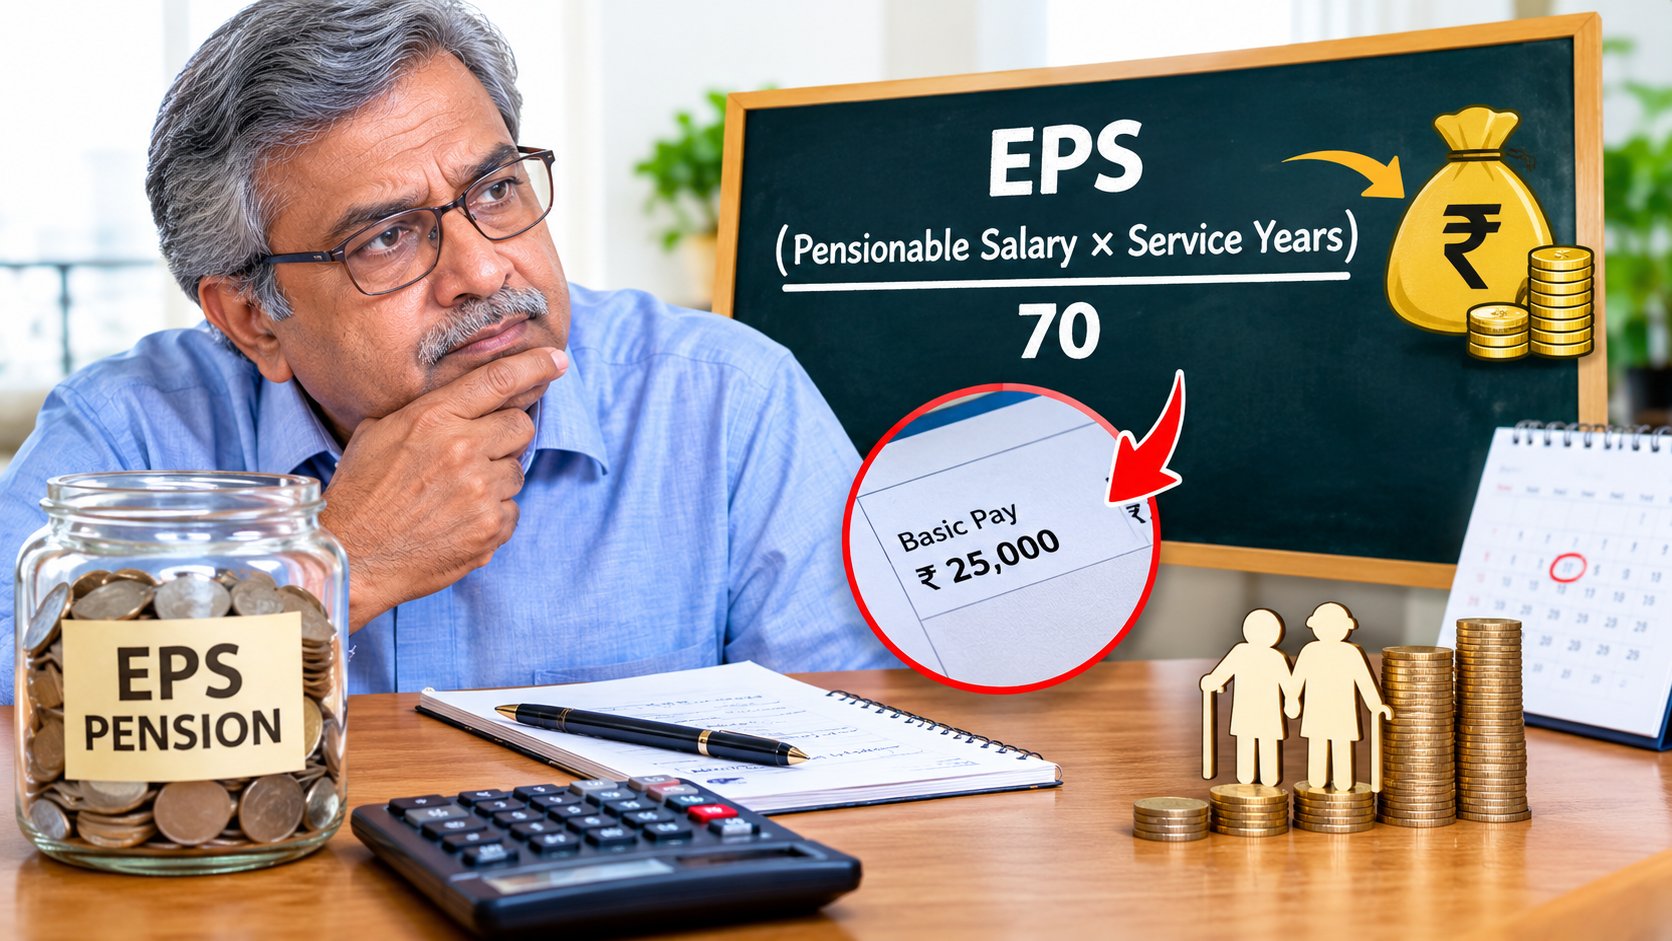
Final payouts suffer as pension formula P=Pensionable Salary×Pensionable Service70P=70Pensionable Salary×Pensionable Service relies on precise history.
Legal and Service Impacts
Errors fuel court cases and grievances, overwhelming EPFO. Uniform guidelines now standardize fixes, but unresolved issues still deny timely access to funds at age 58.



Core Correction Scenarios
EPFO identifies two primary EPS correction scenarios: erroneous enrollment of ineligible members and wrongful exclusion of eligible ones. These guidelines from the December 19, 2025, circular standardize fixes across unexempted (EPFO-managed) and exempted (trust-managed) establishments.
Ineligible Member Enrollment
Employers wrongly remit EPS contributions for non-qualifying employees, such as those earning over ₹15,000 monthly after 2014 or non-employees like directors. EPFO recalculates these amounts with interest at declared rates and transfers funds back—Account 10 (pension) to Account 1 (PF) in unexempted cases or to trusts in exempted ones.
Erroneous pension service entries delete from records to prevent inflated claims. Physical transfers ensure accurate balances, avoiding pension eligibility for ineligible workers.
Eligible Member Exclusion
Qualified employees miss EPS when employers divert full shares to PF accounts instead. Corrections compute due contributions plus interest, transferring from Account 1 to 10 (unexempted) or trusts to EPFO (exempted).
Pensionable service credits apply, including non-contributory periods (NCP) if gaps exist. This restores full eligibility and boosts retirement payouts.
Scenario Comparison
| Scenario | Who Affected | Key Fix | Fund Movement (Unexempted) | Service Change |
| Ineligible Enrollment | High earners, non-employees | Recalculate + interest | Ac 10 → Ac 1 | Delete service |
| Eligible Exclusion | Missed low-wage workers | Due amount + interest | Ac 1 → Ac 10 | Credit service + NCP |
Exempted vs Unexempted Handling
EPFO distinguishes setups managing their own PF trusts (exempted) from direct EPFO-managed ones (unexempted). Below table outlines processes:
| Scenario | Establishment Type | Correction Action | Fund Transfer | Service Update |
| Erroneous EPS for Ineligible | Unexempted | Recalculate with interest | Ac 10 → Ac 1 (EPFO internal) | Delete pension service |
| Erroneous EPS for Ineligible | Exempted | Recalculate with interest | Ac 10 → Trust | Delete pension service |
| Missed EPS for Eligible | Unexempted | Due amount + interest | Ac 1 → Ac 10 (EPFO internal) | Credit service + NCP |
| Missed EPS for Eligible | Exempted | Due amount + interest | Trust → EPFO Ac 10 | Credit service + NCP |
Physical transfers occur wherever needed for precise accounting.
Step-by-Step Correction Process
Employees initiate EPS corrections by reviewing passbooks on the EPFO portal or UMANG app, then coordinating with employers for joint submissions to field offices. The December 2025 circular (WSU/2025/E-961539) mandates employer computation of dues with interest before EPFO verification and fund transfers.
Step 1: Detect Errors
Download EPS passbook and Annexure K from unifiedportal-mem.epfindia.gov.in using UAN. Check for ineligible entries (high earners post-2014) or missing contributions against payslips and Form 3A/6A.
Spot gaps in pensionable service or non-contributory periods (NCP).
Step 2: Notify Employer
Email HR with proof: appointment letters, payslips, bank statements. Request acknowledgment, error computation (principal + 12% compounded interest), and joint declaration preparation.
Current employers handle past ones via coordination; closed firms need affidavits.
Step 3: Submit Joint Request
Employer files online via employer portal with DSC or submits offline (revised Form 3A) to regional EPFO office. Include calculation sheet and documents.
Members forward if employer unresponsive, escalating to EPFIGMS grievances.
Step 4: EPFO Verification and Adjustment
Field office reviews within 15-90 days, adjusts records: deletes wrong service, credits missing ones, executes transfers (Ac 10↔Ac 1 or trust).
Interest applies at EPFO-declared rates; track via portal Case ID.
Step 5: Confirm and Claim
Regenerate passbook/Annexure K; ensure KYC matches before Form 10D at 58. Rejections drop post-correction.
Process Timeline
| Step | Duration | Key Action |
| Detect & Notify | 1-7 days | Self-review + HR email |
| Joint Submission | 2-15 days | Employer files DSC/offline |
| EPFO Processing | 30-90 days | Verification + transfers |
| Confirmation | 7-20 days | New Annexure K |
Benefits for Retiring Workers
Standardization of EPS correction processes across EPFO offices eliminates delays from varying practices, ensuring timely pension approvals under EPS-95.
Interest on recalculated contributions safeguards retirement funds, while restored service credits boost monthly payouts since pensions depend directly on contribution periods.
Exempted trust members gain higher pensions through parallel 2025 reforms allowing accurate higher wage inclusions post-Supreme Court rulings.
Delay Elimination
Inconsistent field office handling previously caused 3-12 month Form 10D backlogs. New uniform guidelines mandate swift verifications and transfers, cutting processing to weeks for clean claims.
Fund and Service Protection
Corrections add interest at EPFO rates (8.25% for 2025-26) on dues, preventing losses. Crediting pensionable service and non-contributory periods (NCP) lifts payouts—each year adds ₹300-₹600 monthly via P=Pensionable Salary×Service70P=70Pensionable Salary×Service.
Exempted Trust Advantages
2025 reforms enable exempted establishments to rectify errors and opt for higher pension calculations on actual salaries (up to ₹15,000 cap waived post-2014). This aligns trusts with EPFO, unlocking 20-50% higher benefits for long-service members.
Benefit Impacts
| Aspect | Pre-Correction Issue | Post-Fix Gain |
| Processing Time | 3-12 months delays | Weeks to approval |
| Monthly Pension | Missing service cuts ₹500+ | Full credits restore amount |
| Fund Value | No interest on errors | 8.25% compounded protection |
| Exempted Reforms | Wage cap limits | Higher actual salary basis |
EPS Eligibility Refresher
Employees earning below ₹15,000 monthly (basic + DA) qualify for mandatory EPS membership since September 2014, with employers diverting 8.33% of their PF share to pension accounts.
Pre-2014 higher earners could opt in; ineligible cases include directors, contractors without employee status, or those over 58 (except deferred pension flags).
Pension eligibility requires 10 years contributory service by age 58, or reduced from 50; corrections now restore missing periods.
Mandatory Enrollment Rules
All EPF members under covered establishments join EPS automatically if wages ≤₹15,000 at joining post-August 2014. Employer contributes max ₹1,250 monthly (8.33% of ₹15,000), regardless of actual pay up to cap.
Opt-out impossible for eligibles; voluntary for pre-2014 high earners via joint option (deadline passed).
Ineligible Categories
- Wages >₹15,000 joining post-2014: Full employer share to EPF.
- Age 58+: Contributions stop unless deferred.
- Non-employees: Proprietors, partners, directors without salary proof.
- <10 years service: Return of Capital (ROC) via Form 10C, no monthly pension.
Service and Claim Basics
Full pension at 58 with 10+ years; early at 50 (4% reduction/year). Formula uses last 60-month average pensionable salary × service /70.
Eligibility Quick Check
| Category | Eligible for EPS? | Contribution Details |
| Wages ≤₹15k (post-2014) | Yes, mandatory | 8.33% employer share (max ₹1,250) |
| Wages >₹15k (pre-2014) | Optional (if opted) | Actual salary basis |
| Age ≥58 | No new contributions | Deferred pension possible |
| <10 yrs service | No monthly pension | Form 10C for lump sum |
Broader 2025 EPFO Reforms
EPS-95 review progresses with proposals for inflation-linked pension formulas and higher contribution caps to match rising costs. Digital claims processing, NPCI-centralized payments, and relaxed withdrawal rules support error corrections by streamlining access.
EDLI coverage expands to ₹7 lakh regardless of PF balance, while housing advances require only 3 years service instead of 5.
EDLI pays ₹7 lakh on death within 60-day contribution gaps—no PF balance needed. Housing advances from PF rise to 90% after 3 years service, aiding first-time buyers.
Reforms Impact
| Reform | Key Change | Benefit |
| EPS Review | Inflation formulas, higher caps | Larger adjusted pensions |
| Digital Claims | Auto-processing, NPCI payments | Instant access nationwide |
| EDLI | ₹7 lakh flat coverage | Stronger family security |
| Housing | 3-year eligibility | Easier home funding |
Steps to Check if my EPS Contributions Have Errors
Access EPFO member portal or UMANG app with activated UAN to download passbook and Annexure K, cross-checking against payslips for EPS errors like missing entries or zero wages.
Step 1: Activate UAN and Login
Visit unifiedportal-mem.epfindia.gov.in or UMANG app. Enter UAN, password, and CAPTCHA; activate via Aadhaar OTP if needed. Download e-passbook for all employers.
Step 2: Review EPF Passbook
Open “Online Services” > “Passbook”. For each employer:
- Check “EPS” column in deduction details: Missing/zero for low-wage periods signals exclusion error.
- Verify dates (DOJ/DOE): Gaps or mismatches indicate service breaks.
- Spot irregular patterns like high EPS for ineligible high earners.
Compare with salary slips/Form 3A/6A from HR.
Step 3: Download Annexure K
Under “Pension” tab, generate Annexure K (EPS service summary). Red flags:
- Missing service years.
- Zero pensionable salary.
- Non-contributory periods (NCP) uncredited.
- KYC mismatches blocking display.
Step 4: Cross-Verify Documents
Match against:
- Payslips (EPS deduction 8.33% of wages ≤₹15,000).
- Bank statements (salary credits).
- Form 11 (prior service declaration).
Step 5: Use Free Checkers and Grievances
Tools like Kustodian EPS checker spot gaps instantly. Raise EPFIGMS grievance if discrepancies found.
Common Error Signs
| Sign | Possible Error | Next Action |
| Zero EPS entries | Eligible exclusion | Contact employer |
| EPS for >₹15k post-2014 | Ineligible enrollment | Request refund calc |
| Service gaps in Annexure K | Missing contributions/NCP | Joint declaration |
| No Annexure K | Data pending | Regenerate post-KYC |
Documents Required to Request EPS Rectification from EPFO
Requesting EPS rectification from EPFO requires specific documents to prove eligibility errors, wages, and service history. Employers typically lead submissions, but members provide supporting proofs via joint declaration.
Core Documents List
- Joint Declaration: Signed by employer and employee confirming error type (ineligible enrollment or eligible exclusion), with calculation sheet of principal + interest.
- Payslips/Form 3A/6A: Monthly salary proofs showing actual wages (≤₹15,000 for eligibility) and missing/wrong EPS deductions.
- Appointment/Relieving Letters: Verify DOJ/DOE, employment status (excluding directors/contractors).
- Bank Statements: Salary credits matching payslips.
- Annexure K/Passbook Extracts: Highlight discrepancies in current EPS records.
Additional for Specific Cases
- Ineligible: Proof of wages >₹15,000 post-2014 or non-employee status (e.g., director DIN).
- Exempted Trusts: Trust audit reports for fund transfers.
- Digilocker: 1-2 docs per parameter (e.g., Aadhaar, PAN).
Submission Table
| Document | Purpose | Mandatory For |
| Joint Declaration + Calc Sheet | Error details & dues | All cases |
| Payslips (3-6 months) | Wage verification | Both scenarios |
| Appointment Letters | DOJ/DOE proof | Service gaps |
| Annexure K | Current record mismatch | EPFO review |
| Bank Statements | Payment trail | All submissions |
Action Timeline for Retirement
Retiring employees should review EPS records at age 55 and initiate corrections 2-3 years before 58 to avoid Form 10D rejections. EPFO processing takes 30-90 days post-submission, but full resolution including interest credits may extend to 6 months.
Age 55-57: Preemptive Check
Download passbook and Annexure K annually. Spot errors like missing service or ineligible contributions; notify employer immediately for joint declaration. Aim to complete by 57 to buffer delays.
Age 57-58: Submission and Processing
Submit employer request to regional office 6-12 months pre-retirement. EPFO verifies, transfers funds, updates service/NCP within 30-90 days. Track via portal Case ID.
Post-58 fixes possible but risk claim holds; no hard deadline exists under new circular.
Post-Retirement Handling
If errors surface after Form 10D, raise EPFIGMS grievance with proof. Courts allow corrections anytime with evidence, but delays cut interim payments.
Timeline Roadmap
| Age/Timing | Action | Expected Duration |
| 55+ | Check records, notify employer | 1-2 weeks self-review |
| 57 | Joint submission to EPFO | 30-90 days processing |
| 58 (pre-claim) | Verify Annexure K update | 1-3 months full resolution |
| Post-58 | Grievance if needed | 3-6 months + appeals |
Employer Responsibilities
Employers must compute erroneous EPS amounts with interest, prepare joint declarations, and submit correction requests to EPFO field offices under the December 19, 2025, circular (WSU/2025/E-961539).
Computation Duties
Calculate principal plus compounded interest at EPFO-declared rates (e.g., 8.25% for 2025-26) for ineligible remittances or missed eligible contributions. Provide detailed sheets showing dates, wages, and adjustments for both exempted trusts and unexempted accounts.
Submission Requirements
File online via employer portal with DSC or offline with revised Form 3A/Annexure K to regional offices. Coordinate physical fund transfers: Ac 10→Ac 1 (unexempted ineligible), Ac 1→Ac 10 (eligible exclusion), or trust↔EPFO.
Maintain KYC, respond to member queries, and face recovery under EPF Act Section 7Q for delays.
Compliance Penalties
Non-response triggers 12% interest, damages, and prosecution; principal employers liable for contractors.
Employer Obligations Table
| Duty | Action Required | Consequence of Delay |
| Error Calculation | Principal + interest sheet | 12% p.a. + damages |
| Joint Declaration | Online/offline submission | Account lock, prosecution |
| Fund Transfers | Ac 10↔1 or trust | Penal recovery |
| KYC Updates | Member records | Claim rejections |
Common Myths Busted
New EPFO guidelines bust myths around EPS corrections, confirming fixes apply anytime with interest and proof, regardless of retirement status. Employees and employers share responsibility, preventing losses from errors.
Myth 1: Corrections Impossible Post-Retirement
Many believe EPS errors can’t fix after age 58 or Form 10D filing. Fact: December 2025 circular enables rectifications anytime via joint declaration or grievances, even during pension processing, with service updates and fund transfers.
Myth 2: No Interest on Rectifications
Claimants think corrections forfeit interest on dues. Fact: EPFO mandates recalculation with compounded interest at declared rates (8.25% for 2025-26), protecting full fund value for both ineligible refunds and eligible credits.
Myth 3: Only Employers Can Initiate
Workers assume sole employer action needed. Fact: Members start via passbook review, employer notification, or direct EPFIGMS grievances if unresponsive; EPFO verifies independently.
Myth 4: Errors Don’t Affect PF Interest
Some say wrong EPS entries halt PF credits. Fact: EPFO continues interest on available EPF balances during corrections; full PF access restores post-transfer.
Myths Busted Table
| Myth | Reality | Source |
| No post-retirement fixes | Anytime with proof | Circular allows during claims |
| Zero interest paid | Full EPFO rates applied | 8.25% compounded on dues |
| Employer-only process | Members initiate/grieve | Joint or individual action |
| Blocks PF interest | Continues on EPF portion | Restores after transfer |
Future Pension Security
The new EPS correction guidelines symbolize a major stride toward secure and transparent retirements in India. Integrated with the EPFO 3.0 digital transformation, these measures pave the way for faster, error-free claim settlements and streamlined coordination between employers, pension offices, and retirees. By addressing contribution mismatches and automating verifications, EPFO is restoring accuracy and trust in pension processing—an area that historically caused uncertainty for millions nearing retirement.
Moreover, the alignment with the ongoing Unified Pension Scheme discussions signals a vision for a seamless national retirement system where portability, digital records, and transparency become the norm. Retirees can now look forward to timely pensions and a system that values precision and accountability. In essence, the reforms ensure that small administrative oversights will no longer undermine a lifetime of work, allowing every retiree to enjoy a dignified and confident post-retirement life.
Disclaimer: The use of any third-party business logos in this content is for informational purposes only and does not imply endorsement or affiliation. All logos are the property of their respective owners, and their use complies with fair use guidelines. For official information, refer to the respective company’s website.