Education · Personal finance · NCERT textbooks, India 2026
NCERT’s New Financial Literacy Lessons: Why Children May Start Learning About SIPs and Money Earlier
NCERT’s new Class 9 Social Science textbook adds a chapter on managing personal finances, covering fixed deposits, mutual funds, risk and return, EMIs and taxes, plus a chapter on startups. SIPs are not named in published descriptions, but the building blocks behind them now sit in the school syllabus.
A 14-year-old today can pay by UPI, watch investing reels and see “no-cost EMI” offers on a shopping app before any adult explains what interest is. Until now, most Indian school textbooks did little to close that gap. Money was taught as history and economics: barter, banks, credit. Not as decisions a student will make.
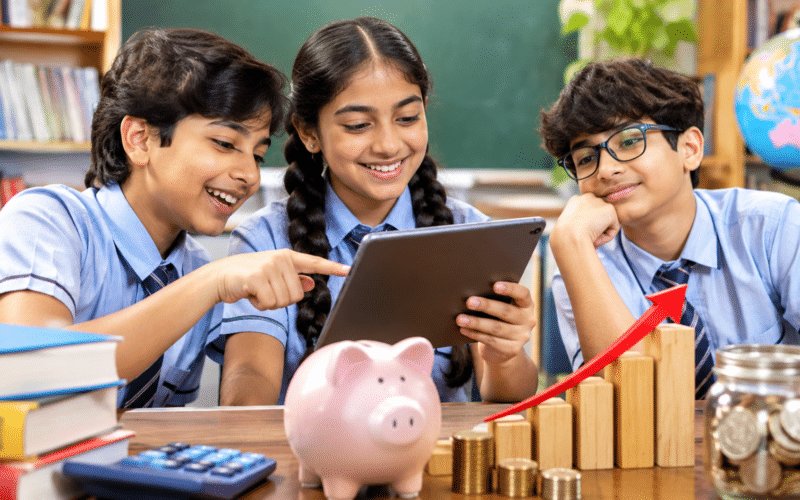
That is beginning to change. NCERT’s new Class 9 Social Science textbook brings personal finance and entrepreneurship into mainstream classrooms for the first time as dedicated chapters. This explainer looks at what the lessons actually cover, what has been overstated, and why the age at which children learn about saving and investing matters so much, with the numbers to show it.
What Is Actually in the New Textbook
The changes became widely known on 3 November 2026, when economist Sanjeev Sanyal, a member of the Prime Minister’s Economic Advisory Council, shared photographs of the pages on X. He wrote that the economics segment of the Grade 9 Part 2 book now has a chapter on personal finance where students learn basics about fixed deposits, mutual funds, EMI, taxes and risk-return, adding that “the idea is to provide them with useful life skills.”
- Chapter 5“Managing Your Personal Finances”
- Chapter 6“From Ideas to Startups”
- 5 areasIncome, budgeting, saving, investing, protection and risk
- 5 productsFDs, government savings schemes, bonds, shares, mutual funds
- 2 tax typesDirect tax such as income tax; indirect tax such as GST
- 4 functionsBusiness areas taught in the startup chapter
According to Outlook Money’s reading of the book, the personal finance chapter is organised around five areas: income, budgeting, saving, investing, and protection and risk management. Students meet fixed deposits, government savings schemes, bonds, shares and mutual funds, and learn that lower-risk products generally offer lower returns. The tax section explains direct and indirect taxes, income tax, GST and the idea of progressive taxation.
The startup chapter changes the tone
Chapter 6, “From Ideas to Startups”, uses the example of students running a lemonade stall at a school festival to explain expenses, pricing, profit and loss. It covers business plans and four functions: management and operations, finance and accounting, human resources, and marketing and sales. Sanyal said this presents risk-taking and innovation positively, unlike earlier textbooks that emphasised “hoarding” and “black-markets”.
Premise check: none of the published descriptions of the chapter, from Business Today, Outlook Money or Sanyal’s own post, mention SIPs by name. The chapter teaches mutual funds and risk and return, which are the foundations of a SIP. Treat “students will learn SIPs” as an inference, not a confirmed syllabus item, until the full chapter text is reviewed.
Money in School Before This: Scattered, Optional, Late
Financial ideas were not entirely absent before. A government reply in Parliament noted that NCERT’s economics content already covered the evolution of money, the banking system, forms of credit and institutions such as the stock exchange, and that Class 11 and 12 economics includes the budget process. CBSE has also offered “Financial Literacy” as an optional skill module in Classes 6 to 8.
The difference is depth and reach. Optional modules reach only schools that choose them. A chapter in the core Social Science textbook reaches every school that uses NCERT books, and it frames money as personal decisions rather than abstract systems. The National Education Policy 2020 had already listed financial literacy among the skills schools should build.
Grade-level placement based on parliamentary replies and NCERT textbook reports. Bar length shows the approximate age at which each lesson is met, scaled to 17 years.
Why Earlier Matters: The Gap Between Knowing and Doing
India’s financial literacy numbers explain the push. The National Centre for Financial Education found that only 27% of Indian adults are financially literate, a figure the World Economic Forum cited in 2025 against an average of 52% in advanced economies. An older S&P Global FinLit survey put India at 24%.
SEBI’s Investor Survey 2025, covering more than 90,000 households, found a striking gap. Sixty-three per cent of households, about 213 million, knew of at least one securities market product, yet only 9.5%, about 32.1 million, actually invested. For mutual funds specifically, Outlook Money reported awareness of 53% but participation of only 6.7%.
SEBI Investor Survey 2025, household-level data, as reported by Moneylife, Outlook Money and Finnovate. Bar length scaled to 63%.
The survey also found that 79.7% of households have a low risk appetite. Awareness, in other words, is not the main barrier. Confidence and understanding are. That is precisely the gap a classroom lesson on risk, return and compounding is meant to address, years before a teenager’s first salary or first loan offer.
Young Indians are already investing, often without lessons
The young are not waiting for the syllabus. NSE’s Market Pulse report for June 2026, as summarised by Finplann and Wealthy, put investors under 30 at 37.9% of the registered base and 59% of new investors in April to June 2026. AMFI data show about 10 crore SIP accounts contributed ₹32,160 crore in October 2026. Many learn about markets from social media; SEBI’s survey flagged “finfluencers” as a growing influence.
The Maths a 14-Year-Old Can Now Understand
Compounding is the reason starting age matters so much, and it is the concept most likely to change behaviour once it clicks. The examples below use a ₹500 monthly SIP, the common minimum, held until age 60.
Worked example: the cost of waiting ten years. Assume ₹500 a month invested at an assumed 10% annual return, compounded monthly. Starting at 25 and stopping at 60, you invest ₹2.1 lakh and end with about ₹19.1 lakh. Start at 35 instead and you invest ₹1.5 lakh and end with about ₹6.7 lakh. Ten years’ delay costs about ₹12.5 lakh of final value for only ₹60,000 less invested. These are our calculations; returns are assumptions, not predictions, and equity returns can be negative over shorter periods.
| Start age (to 60) | Total invested | Value at 7% | Value at 10% | Value at 12% |
|---|---|---|---|---|
| 15 | ₹2,70,000 | ₹19.07 lakh | ₹52.85 lakh | ₹1.08 crore |
| 20 | ₹2,40,000 | ₹13.20 lakh | ₹31.88 lakh | ₹59.41 lakh |
| 25 | ₹2,10,000 | ₹9.06 lakh | ₹19.14 lakh | ₹32.48 lakh |
| 30 | ₹1,80,000 | ₹6.14 lakh | ₹11.40 lakh | ₹17.65 lakh |
| 35 | ₹1,50,000 | ₹4.07 lakh | ₹6.69 lakh | ₹9.49 lakh |
Figures are our calculations for ₹500 a month, compounded monthly, before tax, costs and inflation. They illustrate compounding, not expected returns. A child under 18 can invest only through a minor’s folio operated by a parent or guardian.
Our calculation, monthly compounding, before tax and inflation. Bar length scaled to ₹52.85 lakh.
Inflation is the other half of the lesson. At 6% inflation, ₹1 lakh kept idle for 10 years buys only about ₹55,800 worth of today’s goods, by our calculation. Outlook Money notes the chapter explains how inflation erodes money that earns no return.
What Gets Lost If the Lesson Stops at Returns
Teaching investing to teenagers carries a risk: the exciting part, returns, can crowd out the protective part. The chapter’s inclusion of risk and return, EMIs and protection suggests NCERT is aware of this, but much depends on how teachers handle it.
What people most often get wrong is treating a SIP as a guaranteed savings plan. It is a method of investing in a mutual fund, and the fund’s value rises and falls with markets. The other common mistake is assuming “no-cost EMI” is free. It is still a fixed claim on future income, and it often recovers its cost through the product price or fees.
Teachers will decide whether the chapter sticks
A textbook chapter is only as useful as the lesson built around it. Social Science teachers are trained in history, geography and economics, not in mutual fund categories or tax slabs. Without practical exercises, personal finance can easily become another list of definitions to memorise for an exam. The concepts that change behaviour, such as compounding, the trade-off between risk and return, and the true cost of borrowing, need worked numbers and real situations to land.
Regulators already run free programmes that schools could lean on. SEBI’s training arm, NISM, offers financial education courses for students, and CBSE has run sensitisation programmes on financial literacy and digital tools. Linking these to the new chapter would give teachers ready material rather than leaving each school to improvise.
Five habits worth reinforcing at home
- Give a fixed allowance and let the child plan it across needs and wants for a month.
- Open a savings account in the child’s name and review the passbook or app interest together.
- Explain one EMI the family pays: the amount, the rate and the total cost over the loan.
- Use a free SIP calculator to show how ₹250 or ₹500 a month grows, and what happens in a bad year.
- Discuss one finfluencer video together and check its claims against an official source.
How the Pieces Fit: Timeline of Money in Indian Classrooms
- National Education Policy names financial literacy as a skill schools should build.
- Financial literacy offered as an optional skill module.
- SEBI releases Investor Survey 2025: 63% aware, 9.5% invested.
- Under-30s are 37.9% of NSE’s registered investor base.
- AMFI: ₹32,160 crore SIP inflows from about 10 crore accounts.
- Sanjeev Sanyal shares the new Class 9 personal finance chapter.
- Children’s Day coverage puts the Class 9 lessons in national focus.
What We Know, and What Is Still Unclear
What We Know
- NCERT’s new Class 9 Social Science Part 2 book has a chapter on personal finance and one on startups.
- It covers budgeting, saving, FDs, bonds, shares, mutual funds, risk and return, and taxes.
- CBSE already offered optional financial literacy modules in Classes 6 to 8.
- Only 9.5% of Indian households invest in securities, per SEBI.
What Is Still Unclear
- Whether SIPs are explained by name in the chapter.
- Whether the chapter will be examined in CBSE board-linked assessments.
- How teachers will be trained to teach personal finance.
- Whether similar chapters will reach Classes 6 to 8 or state board textbooks.
Frequently Asked Questions
Has NCERT added financial literacy to the Class 9 syllabus?
Yes. The new Class 9 Social Science textbook, Understanding Society: India and Beyond, Part 2, includes a chapter titled “Managing Your Personal Finances” and another titled “From Ideas to Startups”.
Will NCERT teach students about SIPs?
Published descriptions say the chapter covers fixed deposits, mutual funds, risk and return, EMIs and taxes. SIPs are not named in those reports, though the underlying concepts are taught.
What topics are in the NCERT Class 9 personal finance chapter?
Income, budgeting, saving, investing, and protection and risk management, along with products such as FDs, government savings schemes, bonds, shares and mutual funds, and direct and indirect taxes.
Can a child start a SIP in India?
A minor can hold a mutual fund folio in their own name, but a parent or legal guardian must operate it until the child turns 18. Minimum SIPs start at ₹500, or ₹250 under the Chhoti SIP option.
Why is financial literacy important for school students?
Only about 27% of Indian adults are financially literate, per NCFE. Learning budgeting, interest and risk early helps students avoid costly mistakes with credit, scams and investing later.
Does CBSE have a financial literacy subject?
CBSE offers financial literacy as an optional skill module in Classes 6 to 8. The new NCERT chapter brings personal finance into the core Class 9 Social Science textbook.
Who designed the NCERT personal finance chapter?
The chapter is part of NCERT’s new Social Science textbooks. Economist Sanjeev Sanyal highlighted it publicly; the full authorship of the chapter has not been detailed in published reports.
How much does starting a SIP early make a difference?
By our calculation, ₹500 a month at an assumed 10% grows to about ₹19.1 lakh by 60 if started at 25, but only about ₹6.7 lakh if started at 35. Returns are not guaranteed.
The Short Version
NCERT’s new Class 9 textbook brings personal finance into the core syllabus: budgeting, saving, FDs, mutual funds, risk and return, EMIs and taxes, plus a chapter on starting a business. Reports do not confirm SIPs are taught by name, but the concepts behind them now reach students at about 14. With only 9.5% of households investing and young people already entering markets through apps and social media, that earlier, structured start could narrow the gap between knowing about money and handling it well. Parents can reinforce it at home.