How Many Years of Service Do You Need for an EPFO Pension? The 10-Year Rule, the 36-Month Wait and the 20-Year Bonus
- 6 monthsEarlier minimum for withdrawal
- 36 monthsWait before EPS withdrawal
- 10 yearsPension unlocked
- 20 years2-year bonus added
- Age 58Full pension begins
Retirement · EPFO · Pension eligibility · November 2026
How Many Years of Service Do You Need for an EPFO Pension? The 10-Year Rule, the 36-Month Wait and the 20-Year Bonus
You need at least 10 years of eligible service under the Employees’ Pension Scheme for a monthly pension. Under EPS 2026, people who leave earlier must wait 36 months to withdraw, or can carry their service forward with a Scheme Certificate.
You have worked eight years, across three companies, and you are thinking of quitting to start a business. Your EPF balance looks healthy. But there is a second pot you may never have looked at: your Employees’ Pension Scheme account, built from part of your employer’s contribution. Whether that pot ever pays you a monthly pension depends on one number: years of service. Fall short, and it becomes a one-time payment that, since June 2026, you must wait three years to collect. Keep your service unbroken, and it becomes income for life.
Why ten years is the number that matters
EPFO stressed the rule in an advisory in August 2026, reported by Angel One citing LiveMint: members need at least 10 years of eligible service to qualify for a monthly pension, and premature withdrawals can break their service record. The new Employees’ Pension Scheme, 2026, which replaced EPS-95 from 29 June 2026, kept the 10-year requirement, according to Business Today.
The rule exists because EPS is a pooled pension, not a personal savings account. Short memberships pay into the pool without drawing a lifelong pension from it. Ten years is the point at which the scheme treats you as a long-term member entitled to income for life, and to family pension for your dependants.
- 7 lakh+EPS members who leave within 6 months of service, per a June 2024 Labour Ministry statement
- 30 lakh+Withdrawal benefit claims settled in FY 2023-24
- 29 Jun 2026Date EPS 2026 took effect, replacing EPS-95
- 20 daysDeadline for EPFO to settle complete pension claims
- ₹1,000Minimum monthly pension once eligible
- ₹25,000Wage ceiling from 17 September 2026
The first two figures were cited by Outlook Money in July 2026. They show how many members exit too early to ever earn a pension.
What “eligible service” actually counts
Eligible service is the period for which EPS contributions were made in your name. It is not the same as your total working life, and it is not tied to one employer.
Service adds up across jobs
If you move from one EPF-covered employer to another and keep the same Universal Account Number, your EPS service carries over. The Pension Bazaar guide gives a simple example: 6 years in one firm plus 4 years in another makes 10 years, enough for a pension. The key is not withdrawing your EPS money in between.
What breaks the chain
Settling your EPS when you leave a job resets your pensionable service to zero for that period. So does working for an employer not covered by EPF. Gaps between jobs do not erase earlier service, but they do not add to it either.
Higher wages do not shorten the wait
Some members assume a high salary can make up for fewer years. It cannot. The 10-year rule is about time, not money. A member with 9 years at the ₹25,000 ceiling still gets no monthly pension, while someone with 10 years at ₹8,000 does. Salary decides how big the pension is; service decides whether there is one at all.
What people get wrong: withdrawing the full PF balance, including the pension portion, every time they change jobs. Each withdrawal wipes out that stretch of EPS service. Someone with three jobs of four years each has 12 years of service on paper, but if they settled EPS after each job, they have zero for pension purposes.
The five service bands and what each gets you
- Under 6 monthsSmall withdrawal possible. A June 2024 amendment, reported by Upstox, made members with less than 6 months eligible for withdrawal benefits.
- 6 months to under 10 yearsNo monthly pension. Choose a withdrawal benefit, now payable after a 36-month wait, or a Scheme Certificate to keep service.
- 10 to 19 yearsMonthly pension. Full from 58; reduced by 4% a year from age 50.
- 20 years or more2-year bonus. Two extra years are added to service in the pension formula.
- Age 58Normal pension age. Deferment to 60 raises the pension by about 4% a year.
The 2-year bonus and the deferment to 60 are long-standing EPS rules that EPS 2026 reports say were not changed. Exact deferment factors are set by EPFO.
The 36-month wait: the biggest change for early leavers
Under EPS-95, a member leaving before 10 years could claim the withdrawal benefit soon after exit. Under EPS 2026, Business Today reported, the scheme states that “the member shall become eligible to avail the withdrawal benefit only after the lapse of thirty-six months” from the date the last contribution became due, or on reaching superannuation age, whichever is earlier.
The wait applies only to the EPS portion. Your EPF balance follows separate withdrawal rules, Indian Pay Calculator noted. Outlook Money described the 36 months as a waiting period, not a compulsory hold on rejoining: if you join another covered employer within that time, a Scheme Certificate and carried-forward service may serve you better.
How the withdrawal benefit is calculated
The lump sum equals your pensionable salary at exit multiplied by a factor from a table in the scheme. Outlook Money reported that EPS 2026 uses factors based on completed months of contributory service, where EPS-95’s Table D used completed years and ignored periods of under six months.
₹, lump sum. Factors of 2.07 for 25 months and 2.57 for 31 months as reported by Outlook Money, July 2026. Amounts are salary × factor.
Lump sum or lifelong pension: the maths
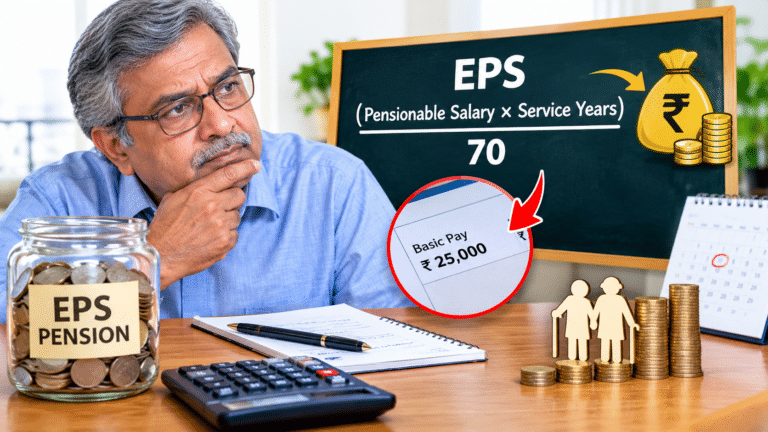
At 10 years, the choice between a withdrawal and a pension changes sharply. The pension formula is pensionable salary times service, divided by 70.
₹ per month at age 58. Our calculation using (salary × service) ÷ 70, adding 2 years of bonus service at 20 years or more.
Worked example: the 10-year pension against a lump sum. At ₹15,000 pensionable salary, 10 years gives a pension of about ₹2,143 a month, or ₹25,716 a year. Over 20 years of retirement, that is about ₹5.14 lakh, before any family pension. A withdrawal at 31 months, by contrast, pays ₹38,550 once. Our calculation, ignoring inflation and the time value of money.
The gap is why carrying service forward with a Scheme Certificate is usually worth it if you expect to work in an EPF-covered job again.
The 20-year jump
Because two bonus years are added at 20 years of service, the step from 19 to 20 years is unusually large.
₹ per month at ₹15,000 pensionable salary. Our calculation; the 2-year bonus applies from 20 years.
One more year of service from 19 to 20 adds about ₹643 a month, more than three times the usual yearly increase of about ₹214. If you are close to 20 years, it may be worth staying in covered employment to cross the line.
Every exit scenario, decoded
| Your service at exit | Monthly pension? | Your options | What to do |
|---|---|---|---|
| Under 6 months | No | Withdrawal benefit, under the 2024 amendment | Keep the UAN active if you may rejoin |
| 6 months to 3 years | No | Withdrawal after 36 months, or Scheme Certificate | Take a certificate if rejoining is likely |
| 3 to 9 years | No | Same two options; lump sum factor grows with months | Strongly consider preserving service |
| 10 years or more, under age 50 | Yes, later | Pension from 50 (reduced) or 58 (full) | Do not withdraw; claim at pension age |
| 10 years or more, age 50 to 57 | Yes, reduced | Early pension with 4% cut a year, or wait | Compare early income against a smaller pension |
| 20 years or more | Yes, with bonus | 2 years added to service | Check bonus is applied on your claim |
| Death or disability in service | Family or disability pension | Payable even with under 10 years, in eligible cases | Keep nominee details updated |
Business Today reported that EPS 2026 retains family pension for eligible dependants and disability pension for permanent, total disablement during service, available with at least one month’s contribution.
How the service rules evolved
- EPS-95 begins, with a 10-year minimum for pension
- Amendment lets members with under 6 months claim withdrawal
- EPS 2026 takes effect; 36-month wait for withdrawal
- Month-based factors reported, e.g. 2.57 at 31 months
- EPFO advisory stresses 10 years of service
- Wage ceiling rises to ₹25,000
- EPFO board meeting; ₹3,000 minimum pension reportedly on agenda
- Normal pension age; early from 50 with 4% a year cut
Protect your service record in six steps
- Use one UAN for your whole career and link it to Aadhaar and your bank account.
- When you change jobs, transfer your PF and EPS to the new employer instead of withdrawing.
- If you leave with under 10 years and may rejoin, apply for a Scheme Certificate with Form 10C.
- Check your passbook every 6 months to confirm EPS contributions are credited.
- Merge any old member IDs so that all service shows against one UAN.
- At 50 or 58, claim pension with Form 10D; EPFO must settle complete claims within 20 days.
Your pension-readiness checklist
- Total EPS service counted across all jobs
- No EPS withdrawals that broke service
- 10-year date noted on your calendar
- 20-year date noted for the 2-year bonus
- Scheme Certificate kept if you left before 10 years
- 36-month wait considered before planning a withdrawal
- Nominee and family details current on the portal
- Monthly EPS deposits checked at ₹1,250 or ₹2,083 if at the ceiling
- Pension age choice made: 50, 58 or 60
- ₹1,000 minimum checked if your salary history is low
EPFO service and pension questions, answered
How many years of service are required for an EPFO pension?
At least 10 years of eligible service under the Employees’ Pension Scheme. Service with different EPF-covered employers counts together if your EPS is transferred rather than withdrawn.
What happens if I leave a job before 10 years?
You can take a withdrawal benefit, which under EPS 2026 is payable only after 36 months from your last contribution or at retirement age if earlier, or get a Scheme Certificate to carry your service forward.
Can I combine service from two companies for pension?
Yes. For example, 6 years in one firm and 4 years in another add up to 10 years, as long as you transferred your EPS and did not withdraw it.
What is a Scheme Certificate in EPS?
A certificate from EPFO that records your EPS service so it can be added to service in a later EPF-covered job, helping you reach 10 years.
How much pension will I get after 10 years?
At a pensionable salary of ₹15,000, 10 years gives about ₹2,143 a month at 58, using the formula salary × service ÷ 70, or the ₹1,000 minimum if the formula gives less.
Is there any bonus for 20 years of service?
Yes. Two years are added to pensionable service for members with 20 or more years, which raises the pension by about ₹428 a month at a ₹15,000 salary.
At what age can I get EPS pension?
Full pension starts at 58. You can start from 50 with a 4% reduction for each year before 58, or defer it to 60 for a higher amount.
Can I get EPS pension with 5 years of service?
No monthly pension. You can claim a withdrawal benefit after the 36-month wait or keep a Scheme Certificate to add those 5 years to future service.
The short version
You need 10 years of eligible service for a monthly EPFO pension. Service from different employers counts if you transfer your EPS instead of withdrawing it. Leave earlier, and EPS 2026 gives you two choices: a lump-sum withdrawal you can claim only after 36 months, or a Scheme Certificate that keeps your service for a future job. Reach 20 years and two bonus years are added. Full pension starts at 58, with reduced pension from 50. At a ₹15,000 salary, 10 years means about ₹2,143 a month; protecting your service record is what makes it happen.