How EPS Pension Is Calculated for Private Employees in 2026 — the ÷70 Formula, the New ₹25,000 Ceiling and Worked Examples
- SalaryAverage of last 60 months
- ×
- ServiceYears of EPS membership
- ÷
- 70Fixed divisor
- =
- PensionPer month, from age 58
Retirement · EPFO · EPS 2026 · November 2026
How EPS Pension Is Calculated for Private Employees in 2026 — the ÷70 Formula, the New ₹25,000 Ceiling and Worked Examples
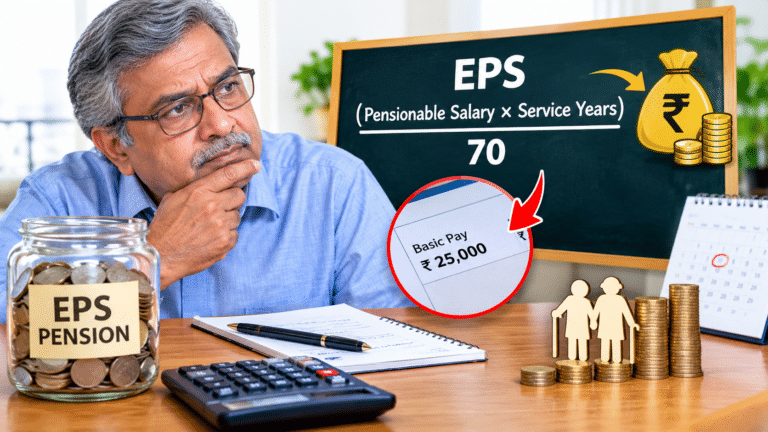
Your monthly EPS pension equals pensionable salary multiplied by years of service, divided by 70. The wage ceiling rose from ₹15,000 to ₹25,000 on 17 September 2026, and EPFO’s board may consider a higher ₹3,000 minimum pension on 19 November.
Every month, 12% of your basic pay goes to EPF, and your employer adds its own share. What most salaried people do not realise is that part of the employer’s money never reaches the PF balance they check on the app. It goes to the Employees’ Pension Scheme instead, and it buys a monthly pension for life after 58. How much that pension will be is a question most private employees cannot answer, even though the formula fits on one line. In 2026 the rules have also shifted: a new scheme replaced EPS-95 in June, the wage ceiling rose in September, and a higher minimum pension is on the EPFO board’s agenda.
Where your EPS money comes from
You do not contribute to EPS directly. Your 12% goes to EPF. Of the employer’s 12%, 8.33% of wages up to the ceiling is diverted to EPS, and the rest goes to EPF. The central government adds 1.16%, which Kotak Neo reported remains calculated on wages up to ₹15,000, a maximum of ₹174 a month per employee.
- 8.33%Employer’s share that goes to EPS
- ₹2,083New maximum monthly EPS contribution at ₹25,000
- ₹1,250Old maximum at the ₹15,000 ceiling
- 1.16%Central government’s contribution, up to ₹174
- 51 lakhExtra workers brought under mandatory coverage
- 20 daysDeadline for EPFO to settle complete pension claims under EPS 2026
The September change matters because the employer’s EPS contribution is capped at 8.33% of the ceiling. CorpLawUpdates, citing gazette notification S.O. 5109(E), reported that the ceiling rose from ₹15,000 to ₹25,000 with effect from 17 September 2026, lifting the maximum EPS contribution from ₹1,250 to ₹2,083 a month. It was the first revision since September 2014.
EPS-95 is now EPS 2026, but the formula did not change
Business Today reported on 2 July 2026 that the Employees’ Pension Scheme, 2026, notified under the Code on Social Security, 2020, replaces EPS-95 and the 1971 family pension scheme. It applies to new members from 29 June 2026, and existing members move across automatically.
The calculation people care about is untouched: pension still equals pensionable salary times pensionable service divided by 70, pensionable salary is still the 60-month average, the qualifying service is still 10 years, and the minimum pension is still ₹1,000. What changed is administration. EPFO must settle complete pension claims within 20 days, and delays without good reason attract 12% annual interest, according to the same report.
Each part of the formula, explained
| Term | What it means | Current limit or rule | Common mistake |
|---|---|---|---|
| Pensionable salary | Average monthly wages in the 60 months before exit | Capped at the wage ceiling, now ₹25,000 | Using your last salary instead of the 60-month average |
| Pensionable service | Total years of EPS membership across employers | Minimum 10 years for a pension | Forgetting to merge service from old jobs |
| Bonus service | Extra weightage for long careers | 2 years added for 20 or more years of service | Leaving it out of the calculation |
| Divisor | Fixed number that converts salary-years into monthly pension | 70 | Dividing by 12 or by 60 |
| Retirement age | Age for full pension | 58; reduced pension from 50 | Assuming pension starts at 60 |
| Minimum pension | Floor on monthly pension | ₹1,000, a ₹3,000 proposal is pending | Thinking the minimum applies to early-exit withdrawals |
The 2-year bonus for 20 or more years of service is a long-standing EPS rule. EPFO’s Scheme Certificate lets you carry service from one employer to the next; withdrawing your EPS balance when leaving a job breaks that chain.
Worked examples at the old ₹15,000 ceiling
Most people retiring in the next few years will have spent their careers under the ₹15,000 ceiling. Their pension is calculated on wages up to that cap, regardless of how much they actually earned, unless they opted for higher pension.
Example 1: 20 years of service. Pensionable salary ₹15,000. Service 20 years, plus the 2-year bonus, makes 22. Pension = 15,000 × 22 ÷ 70 = about ₹4,714 a month. Our calculation.
Example 2: 12 years on lower wages. Pensionable salary ₹8,000, service 12 years. Pension = 8,000 × 12 ÷ 70 = about ₹1,371 a month.
Example 3: when the minimum kicks in. Pensionable salary ₹5,000, service 10 years. The formula gives about ₹714, so the ₹1,000 minimum pension applies instead.
₹ per month at age 58. Our calculation using (salary × service) ÷ 70, with the 2-year bonus added for 20 or more years. The ₹25,000 bars are hypothetical: they assume the whole 60-month average and all service are at the new ceiling, as for someone who joins now.
What people get wrong: assuming the ₹25,000 ceiling instantly raises the pension of someone retiring next year. Pensionable salary is a 60-month average. A person retiring in 2027 will have only a few months at the higher ceiling in that average. When the ceiling last rose in 2014, from ₹6,500 to ₹15,000, pension for earlier service was widely reported to be calculated on the old ceiling. How EPFO will treat service before 17 September 2026 has not been spelled out in the reports we reviewed.
Retire early, wait longer: how age changes the cheque
Full EPS pension begins at 58. You can start drawing it from age 50, but the amount is cut by 4% for each year before 58, as the EPS 2026 rules retain. You can also defer it to 60, which raises the pension by about 4% for each year of deferment.
- Age 50Earliest start; 8 years early, so 32% lower₹3,206
- Age 553 years early, so 12% lower₹4,149
- Age 58Normal pension age; full formula amount₹4,714
- Age 591 year deferred, about 4% higher₹4,903
- Age 602 years deferred, about 4% a year, compounded₹5,099
Figures use Example 1’s ₹4,714 at 58 and are our calculations; deferment is shown compounded at 4% a year, and EPFO’s exact factors may differ slightly. An early start may still make sense if you need income at 55; the decision is permanent, so compare it with other income you will have.
Why many pensions sit near ₹1,000, and what the board may change
Low wages, broken service and a ceiling that stayed at ₹15,000 for 12 years have kept many EPS pensions small. The ₹1,000 minimum was introduced in August 2014, after board approval in February 2014, Angel One reported. Pensioner groups have long sought ₹7,500 a month.
₹ per month. Sources: Angel One and Free Press Journal on the 240th CBT meeting agenda, November 2026. The ₹3,000 proposal has not been confirmed by the Labour or Finance ministries.
The maximum figure is our calculation for 35 years of pensionable service at the old ceiling, the cap commonly cited for EPS service. The 240th meeting of EPFO’s Central Board of Trustees is scheduled for 19 November 2026 at EPFO’s head office in New Delhi. A reported agenda item would raise the minimum to ₹3,000. Until it is approved and notified, the minimum stays at ₹1,000.
The budget behind the ceiling hike
CorpLawUpdates reported that the government expects to spend ₹56,696 crore over five years on the ceiling change, with annual central support rising from ₹10,250 crore to ₹11,339 crore. That is ₹1,089 crore more each year, covering an additional 51 lakh workers who now fall under mandatory EPF coverage.
₹ crore. Source: CorpLawUpdates, citing the Cabinet decision and PIB, September 2026.
The higher-pension exception, and family pension
Not everyone’s pensionable salary is capped. After the Supreme Court’s November 2022 ruling, some members and employers opted to contribute on actual wages above the ceiling, a route known as higher pension. For them, pensionable salary is their real average wage, which can produce a much larger pension. Business Today reported that EPS 2026 formally writes higher pension into the scheme, so members already on it keep the benefit, with an effective employer contribution of 9.49% on salary above the ceiling.
EPS also pays family pension to an eligible spouse, children, nominees or dependent parents after a member’s death, and an orphan pension at 75% of the widow pension where no spouse survives. A disability pension is available for permanent, total disablement during service even without 10 years of membership, provided at least one month’s contribution has been made.
How the rules evolved
- Employees’ Pension Scheme, 1995 begins.
- Wage ceiling raised from ₹6,500 to ₹15,000; ₹1,000 minimum pension takes effect from August.
- EPS 2026 replaces EPS-95 under the Code on Social Security, 2020.
- Cabinet approves a ₹25,000 wage ceiling.
- New ceiling takes effect; maximum EPS contribution becomes ₹2,083.
- EPFO enables contribution filing at the new limit.
- 240th CBT meeting; ₹3,000 minimum pension reportedly on the agenda.
Check your own EPS pension in six steps
- Log in to the EPFO member portal and open your passbook for each member ID.
- Add up EPS service across all employers; check old IDs are linked to your UAN.
- Note the EPS contribution in each month; at ₹1,250 or ₹2,083 you are at the ceiling.
- Estimate pensionable salary as the average wage up to the ceiling for your last 60 months.
- Apply (salary × service) ÷ 70, adding 2 years if service is 20 or more.
- Apply 4% a year cuts for an early start, or add about 4% a year if you defer to 60.
Protect your pension: a checklist
- Do not withdraw EPS when changing jobs if you have under 10 years
- Take a Scheme Certificate to carry service forward
- Merge old member IDs with your UAN
- Check employer EPS deposits each month on the passbook
- Know your service total; 10 years is the threshold
- Remember the 2-year bonus at 20 years of service
- Think hard before drawing pension at 50 with a 32% cut
- Keep nominee and family details updated for family pension
- File Form 10D to claim pension; EPFO must settle in 20 days
- Watch the 19 November board outcome on the ₹1,000 minimum
EPS pension questions private employees ask
How is EPS pension calculated?
Monthly pension = (pensionable salary × pensionable service) ÷ 70. Pensionable salary is the average of wages, up to the ceiling, over the last 60 months before exit.
What is the EPS wage ceiling in 2026?
₹25,000 a month from 17 September 2026, up from ₹15,000. The maximum employer EPS contribution rose from ₹1,250 to ₹2,083.
How much pension will I get after 20 years of service?
At a pensionable salary of ₹15,000, 20 years plus the 2-year bonus gives 15,000 × 22 ÷ 70, or about ₹4,714 a month at 58.
What is the minimum EPS pension?
₹1,000 a month. A proposal to raise it to ₹3,000 is reportedly on the agenda of EPFO’s board meeting on 19 November 2026, but it has not been approved.
Can I get EPS pension before 58?
Yes, from age 50, with a 4% reduction for each year before 58. Starting at 50 means a pension about 32% lower.
What happens to EPS if I have less than 10 years of service?
You cannot get a monthly pension. You can withdraw the eligible amount or take a Scheme Certificate to carry service forward to your next job.
Has EPS-95 been replaced?
Yes. The Employees’ Pension Scheme, 2026, under the Code on Social Security, 2020, replaced EPS-95 from 29 June 2026. The formula, 10-year rule and ₹1,000 minimum are unchanged.
What is the maximum EPS pension?
No maximum is fixed in rupees. At the old ₹15,000 ceiling, 35 years of service gives about ₹7,500 a month; the new ₹25,000 ceiling will allow more for future service.
The short version
EPS pension for private employees is calculated as pensionable salary times years of service divided by 70. Pensionable salary is the 60-month average, capped at the ceiling, which rose to ₹25,000 on 17 September 2026. You need 10 years of service; long careers get a 2-year bonus; full pension starts at 58, with 4% cuts a year from 50. At the old ceiling, 20 years gives about ₹4,714 a month. The minimum is ₹1,000, and EPFO’s board may consider ₹3,000 on 19 November. Keep your service unbroken and your IDs merged.