Can Nifty 50 Hold 23,000 After a Seven-Week Losing Streak?
Markets · Dalal Street Briefing · Monday, 28 September 2026
Can Nifty 50 Hold 23,000 After a Seven-Week Losing Streak?
By the Dailyfinancial.in Markets Desk · Figures checked against NSE and BSE closing data, NSDL flow data, RBI, MoSPI and PIB releases, and reports from Mint, Business Standard and Upstox · Market data as of market close, Friday 25 September 2026, with pre-open cues as of 8:20 AM IST, Monday 28 September 2026
Quick Summary: The Numbers That Matter This Morning
The Sensex and Nifty 50 bounced on Friday but still closed a seventh straight losing week, the longest such run in about six years. GIFT Nifty points to a softer Monday start near 23,110 to 23,118, so the 23,000 floor is the level every trader is watching.
BSE Sensex
73,895.74
+315.20 (+0.43%)
NSE Nifty 50
23,140.50
+77.40 (+0.34%)
Bank Nifty
55,580.40
+0.26%
India VIX
12.18
-4.00%
FII / DII net
-₹3,694 cr / +₹2,838 cr
Cash market, 25 Sep
Top sector
Nifty Realty
+0.92%
Seven weeks without a single weekly gain. The Nifty 50 has lost 3.90% in September alone, and on Thursday, 24 September, the Sensex shed 1,247.71 points in its worst session in about six months before clawing back only a quarter of that on Friday.
This briefing on the Indian stock market today explains what happened, why, and what to do next: BSE Sensex, NSE Nifty 50 and Nifty Bank trend, India GDP growth, CPI inflation and RBI repo rates, global cues, sector performance India 2026, sixteen stock screens, trade ideas and model portfolios.
Indian Market Overview: Why Did Dalal Street Bounce on Friday Yet Still Lose Another Week?
The BSE Sensex swung between 73,477.77 and 73,968.05 before settling at 73,895.74, up 315.20 points or 0.43%, per BSE data, with 19 of 30 stocks higher.
The NSE Nifty 50 gained 77.40 points, or 0.34%, to close at 23,140.50 as of market close, 25 September 2026. It defended 23,000 after a low near 23,030; 34 constituents rose and 15 fell.
| Indicator (25 Sep 2026 close) | Level | Change | What It Tells You |
|---|---|---|---|
| BSE Sensex | 73,895.74 | +0.43% (+315.20 pts) | Off Thursday’s three-month low |
| NSE Nifty 50 | 23,140.50 | +0.34% (+77.40 pts) | 12.3% below 52-week high |
| Bank Nifty | 55,580.40 | +0.26% (+141.90 pts) | Private banks led |
| Nifty Midcap 100 | 60,906.00 | -0.14% | Lagged large caps |
| Nifty Smallcap 100 | 19,715.25 | +0.15% | Mild recovery |
| India VIX | 12.18 | -4.00% | Fear cooled |
| NSE advances / declines | 1,924 / 1,592 | Ratio 1.21 | Positive |
| 52-week highs / lows (NSE) | 90 / 120 | More lows than highs | Weakness persists |
| NSE market capitalisation | ₹477.05 lakh crore | Close | Investor wealth |
Who Was Buying, and Who Was Selling?
Provisional NSE data show FIIs were net sellers of ₹3,694 crore on Friday (bought ₹12,327 crore, sold ₹16,021 crore), while DIIs were net buyers of ₹2,838 crore.
NSDL data show FIIs have sold ₹17,131 crore of Indian equities in September and ₹2,41,572 crore in 2026. SIP-fed domestic funds are absorbing the supply, which is why the fall has been grinding rather than panicky.
Sachin Gupta of Choice Equity Broking calls the Sensex outlook sideways to bearish, with 73,200 to 73,450 as crucial support and 74,000 as the trigger for a move towards 74,500. Rupak De of LKP Securities notes the Nifty is still making lower highs and lower lows.
Our read: sentiment is cautious, not capitulating. Falling volatility and steady DII buying suggest sellers are tiring, but no reversal is confirmed until the Nifty closes above 23,300.
Key Economic Drivers: Is India’s Macro Story Strong Enough to Offset Global Pain?
India’s economy is growing faster than almost any major peer, yet its market has fallen for seven weeks. The answer lies in oil, bond yields and inflation, not domestic demand.
India GDP Growth: Why a 7.8% Print Has Not Lifted Stocks
According to MoSPI data released on 31 August 2026, real GDP grew 7.8% in April to June 2026 (Q1 FY27), above the RBI’s 7% projection and the 6.9% of Q1 FY26, though slower than the 8.6% of January to March 2026.
Manufacturing grew 9.2%, services 10% and investment (GFCF) 11.9%, while agriculture eased to 3.6%. The RBI projects FY27 growth at 6.7%; CareEdge Ratings says 7.3%.
What this means for markets: Strong growth supports bank, capital goods and consumption earnings over 12 to 24 months, but cannot override a spike in global yields in the short run.
CPI Inflation Trend: Is the Oil Shock Now Showing Up in Prices?
Retail inflation measured by CPI rose to 4.82% in August 2026 from 4.45% in July and 4.38% in June, according to MoSPI. Rural inflation ran at 5.23% against 4.31% in urban India, and food and beverages contributed 2.09 of the 4.82 percentage points.
Jewellery alone added 0.71 percentage points as gold and silver surged, so inflation excluding jewellery was about 4.16%.
What this means for markets: Inflation is inside the RBI’s 2% to 6% band but rising, which rules out near-term rate cuts for realty and NBFCs.
RBI Repo Rate: Why the Central Bank Is Sitting Tight at 5.25%
The RBI’s Monetary Policy Committee held the repo rate at 5.25% on 5 August 2026, its fourth consecutive pause, with a neutral stance. The Standing Deposit Facility is at 5.00% and the Marginal Standing Facility and Bank Rate at 5.50%.
The RBI projects inflation at 5.9% for October to December 2026. Meanwhile, the US Federal Reserve raised rates to 3.75% to 4% in mid-September, its first hike in three years, and the rupee sits at 95.81 per dollar.
What this means for markets: With the Fed tightening and the RBI on hold, the rate gap that attracts foreign money is narrowing, a core reason FIIs keep selling.
Jobs Data (PLFS): Is the Labour Market Holding Up?
The Periodic Labour Force Survey bulletin for August 2026 shows the unemployment rate for persons aged 15 and above eased to 5.0% from 5.1% in July. Rural unemployment fell to 4.1% and urban stayed near 6.8%.
Separately, gross GST collections for August 2026 stood at ₹1,99,853 crore, up 14.8% year on year, a clean signal that consumption is intact.
What this means for markets: Resilient demand favours two-wheelers, FMCG volumes and rural lenders once the global storm passes.
Nifty Today: What Do Friday’s Candle and Option Data Say About Monday?
Here is the Nifty 50 technical snapshot as of market close, 25 September 2026, and what pre-open signals suggest for Monday.
- Open: 23,035, below Thursday’s close of 23,063.10.
- High: 23,162.70.
- Low: 23,030, briefly below the 11 June low of 23,072.
- Close: 23,140.50, up 77.40 points or 0.34%.
- Pivot point (desk calculation): 23,111; R1 23,192, R2 23,244; S1 23,059, S2 22,978.
- Support levels: 23,000 first, then 22,900, then 22,700, per LKP Securities and Choice Broking.
- Resistance levels: 23,200 to 23,300, then 23,370, per Sumeet Bagadia of Choice Broking.
- Open interest: maximum Call OI at 24,000 (156.10 lakh contracts); maximum Put OI at 23,000 (144.35 lakh contracts).
- Put-Call Ratio: 0.93 at the at-the-money 23,150 strike, a neutral reading, ahead of Tuesday’s weekly expiry.
- Candlestick pattern: bullish candle opening near the low and closing near the high, a short-covering bar without reversal confirmation.
- Pre-open signal: GIFT Nifty near 23,110 to 23,118.50, about 69 to 77 points lower.
- Trend verdict: short-term trend down; index below key moving averages.
- Outlook for the session: expect a test of 23,000; holding it favours a 22,900 to 23,370 range, while a close below 22,900 opens 22,700.
BSE Sensex vs Nifty 50 in September 2026: Which Index Bled More?
Closing data from BSE and NSE for every September session. Markets were shut on 14 September for Ganesh Chaturthi. Month-to-date (MTD) change is against the 31 August closes of 76,957.27 and 24,080.40.
| Date (2026) | Sensex Close | Sensex Day % | Nifty 50 Close | Nifty Day % | Sensex MTD % | Nifty MTD % |
|---|---|---|---|---|---|---|
| 1 Sep | 76,944.28 | -0.02% | 24,055.80 | -0.10% | -0.02% | -0.10% |
| 2 Sep | 76,570.35 | -0.49% | 23,914.45 | -0.59% | -0.50% | -0.69% |
| 3 Sep | 76,152.86 | -0.55% | 23,873.45 | -0.17% | -1.05% | -0.86% |
| 4 Sep | 76,515.43 | +0.48% | 23,897.70 | +0.10% | -0.57% | -0.76% |
| 7 Sep | 76,132.81 | -0.50% | 23,779.15 | -0.50% | -1.07% | -1.25% |
| 8 Sep | 75,577.58 | -0.73% | 23,635.10 | -0.61% | -1.79% | -1.85% |
| 9 Sep | 74,764.23 | -1.08% | 23,431.50 | -0.86% | -2.85% | -2.69% |
| 10 Sep | 74,902.59 | +0.19% | 23,477.80 | +0.20% | -2.67% | -2.50% |
| 11 Sep | 74,781.76 | -0.16% | 23,398.10 | -0.34% | -2.83% | -2.83% |
| 15 Sep | 74,003.82 | -1.04% | 23,118.60 | -1.19% | -3.84% | -3.99% |
| 16 Sep | 74,336.45 | +0.45% | 23,217.60 | +0.43% | -3.41% | -3.58% |
| 17 Sep | 74,314.59 | -0.03% | 23,270.60 | +0.23% | -3.43% | -3.36% |
| 18 Sep | 74,294.96 | -0.03% | 23,346.40 | +0.33% | -3.46% | -3.05% |
| 21 Sep | 74,858.99 | +0.76% | 23,414.30 | +0.29% | -2.73% | -2.77% |
| 22 Sep | 74,529.08 | -0.44% | 23,329.00 | -0.36% | -3.16% | -3.12% |
| 23 Sep | 74,828.25 | +0.40% | 23,446.80 | +0.50% | -2.77% | -2.63% |
| 24 Sep | 73,580.54 | -1.67% | 23,063.10 | -1.64% | -4.39% | -4.22% |
| 25 Sep | 73,895.74 | +0.43% | 23,140.50 | +0.34% | -3.98% | -3.90% |
The Sensex has lost slightly more this month, 3.98% against 3.90% for the Nifty. Out of 18 sessions, the Sensex fell in 12 and the Nifty in 10, so the broader 50-stock index has shown a little more resilience.
The two worst days, 15 and 24 September, both coincided with jumps in crude and US yields, which shows where the real driver sits.
Latest Market News Highlights: Which Headlines Are Moving Your Portfolio?
- IRDAI commission caps hit financials: the regulator proposed limits on insurance distribution commissions. PB Fintech crashed 36% in one session, erasing about ₹31,400 crore, and Bank Nifty fell 1.96% on 24 September. Comments are open until 25 October.
- US 10-year yield at a 2007 high: it settled near 5.165% on Friday and the 30-year hit 5.53%. That pulls money from emerging markets.
- Trump rejects Iran’s peace plan: the Hormuz stand-off continues, though more talks are expected this week. Brent rose over 1% to $105.64 on Monday, a negative for paints and airlines.
- NSE’s muted debut: the ₹22,562 crore IPO, subscribed 5.71 times at ₹1,785, listed at ₹1,800 on 24 September and touched ₹1,878.
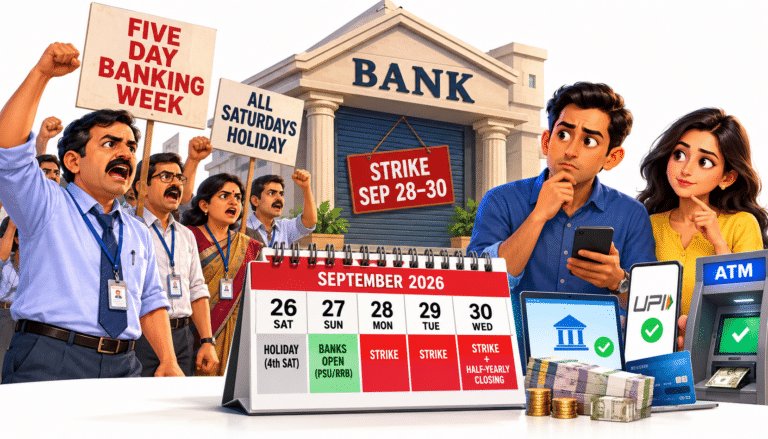
- Bank strike, 28 to 30 September: NSE and BSE trade normally from 9:15 AM to 3:30 PM, though branch services may be hit.
- TCI buyback plan: the board meets on 29 September; the stock jumped as much as 14.6% to ₹955 on about 83 times normal volume.
- Engineers India and Dangote: a mandate to expand the Dangote refinery to 1.4 million barrels a day lifted the stock 7.4% to a 52-week high.
Global Cues: Which Foreign Markets Are Pulling Indian Stocks Lower?
The table below shows the latest closes. US and European figures are for Friday, 25 September; the KOSPI figure is for 23 September because Korea was shut for Chuseok on 24 and 25 September; GIFT Nifty is the early Monday quote.
| Index | Latest Close | Change | Signal for India |
|---|---|---|---|
| Dow Jones | 51,828.62 | +0.93% | Positive |
| S&P 500 | 7,743.41 | +0.51% | Positive |
| Nasdaq Composite | 27,068.72 | +0.48% | Record close |
| GIFT Nifty (Mon, early) | 23,110 to 23,118.50 | Down 69 to 77 pts | Softer open |
| Nikkei 225 | 66,364.20 | +1.30% | Fifth straight gain |
| Hang Seng | 24,510.09 | -1.01% | Negative |
| Shanghai Composite | 3,888.37 | -1.22% | Fell 1.1% Monday |
| KOSPI (23 Sep) | 7,080.92 | +0.90% | Fell 2% Monday |
| FTSE 100 | 10,695.25 | +0.14% | Neutral |
| DAX | 25,408.64 | +0.56% | Positive |
| CAC 40 | 8,077.80 | -0.04% | Flat |
| Macro Asset | Level | Change | Why It Matters for India |
|---|---|---|---|
| US Dollar Index | 101.04 | -0.25% | Eases rupee pressure |
| US 10-year Treasury yield | 5.165% | +0.3 bp | Drains EM flows |
| Brent crude (Fri settle) | $104.32/bbl | -2.14% | $105.64 on Monday |
| WTI crude (Fri settle) | $92.41/bbl | -2.33% | Down 8% on week |
| Gold | $4,320.50/oz | +0.52% | Lifts CPI via jewellery |
| USD/INR | 95.81 | Flat | Raises import costs |
- Wall Street: AI-led gains lifted US indices, but high US yields limited the benefit for Indian IT.
- GIFT Nifty: its 69 to 77 point discount implies a Monday open near 23,050 to 23,070.
- Crude and yields: India’s worst September sessions matched spikes in Brent and US yields, and both remain the dominant forces.
Performance Overview: Which NSE and BSE Stocks Are Breaking Out, and Which Are Breaking Down?
Screens use data as of market close, 25 September 2026 unless a date is stated. Treat them as research starting points, not buy lists.
Daily Fresh Breakouts: Who Broke Out on Friday?
Screen: new 52-week high or a large volume-backed gain on 25 September.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Transport Corp of India | 942.85 (midday) | +13.13% | 82.79x average volume | Buyback meeting 29 Sep |
| Engineers India | 315.65 | +6.40% | 52-wk high ₹318.90 | Dangote refinery deal |
| Zydus Lifesciences | 1,203.90 | +2.00% | 52-wk high ₹1,208.60 | Fifth straight gain |
| Welspun Corp | 2,832.40 | 0.18% below high | Q1 PAT +198.6% | Gap-up of 3.24% |
| Axis Bank | 1,222.40 | +3.03% | 69.2 lakh shares traded | Top Nifty gainer |
Weekly Breakouts: Which Stocks Gained Momentum All Week?
Screen: fresh highs or the strongest multi-session gains, 21 to 25 September.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Pearl Global Industries | 1,353 (Fri high) | +6.12% | MOFSL target ₹1,500 | Buy rating reiterated |
| Bajaj Finance | 996.90 | +1.52% | +3.41% on 23 Sep | NBFC leadership |
| Hindalco Industries | 977.00 | -0.50% | +3.17% on 23 Sep | Record copper prices |
| Welspun Investments | 2,288.85 (23 Sep) | +4.04% in 2 days | 1-yr gain 124.40% | All-time high |
| Supreme Industries | 3,544.00 | +3.38% | Zero debt | Top Midcap 100 gainer |
Oversold Stocks: Where Has Selling Gone Too Far?
Screen: large caps at or near 52-week lows after steep falls; confirm RSI below 30 on your chart.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| PB Fintech | 1,166.00 | 4.57% above low | 1-yr return -33.41% | 36% one-day crash |
| Maruti Suzuki | 12,004.05 | 0.61% above low | 1-yr return -26.12% | Five straight losses |
| Tata Motors PV | 290.45 | -1.54% | Down 18% this quarter | Weak car demand |
| TCS | 2,082.00 | -0.24% | 1-yr return -31.41% | IT index 30% off peak |
| Infosys | 1,000.20 | -1.41% | -11.5% since 24 Aug | US yield pressure |
Stocks Nearing Breakout: Who Is Knocking on Resistance?
Screen: within about 6% of a clear resistance or 52-week high.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Asian Paints | 2,444.00 | 1.89% below ₹2,490.10 | 20-day EMA hurdle | Double bottom |
| SPR Auto Technologies | 4,746.80 | 0.89% below high | 52-wk high ₹4,789.10 | Fresh peak |
| Indegene | 608.95 | 2.13% below high | 52-wk high ₹621.95 | MOFSL target ₹708 |
| SEDEMAC Mechatronics | 3,444.90 | 2.93% below high | 52-wk high ₹3,545.90 | Fresh peak |
| Allied Blenders | 715.05 | 5.42% below high | 52-wk high ₹753.80 | Promoter sale overhang |
Short-Term Buys: Which Ideas Suit a Two-to-Six-Week View?
Screen: named analyst calls or brokerage Buy ratings with defined levels.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Mahindra and Mahindra | 3,035.00 | +1.75% | Stop ₹2,896 to ₹2,900 | Sumeet Bagadia buy |
| Asian Paints | 2,444.00 | +2.14% | Target above ₹2,490.10 | Sumeet Bagadia buy |
| HCL Technologies | 1,258.00 | +1.16% | Stop ₹1,200 | Sumeet Bagadia buy |
| Pearl Global Industries | 1,353 (Fri high) | +6.12% | Target ₹1,500 | MOFSL Buy |
| Indegene | 608.95 | 2.13% below high | Target ₹708 | MOFSL Buy |
FII Holding Changes: Where Is Foreign Money Moving?
Screen: June 2026 quarter shareholding, per filings, Elara Securities and Tijori Finance.
| Stock / Segment | Latest FII Position | Direction | What It Signals |
|---|---|---|---|
| IndusInd Bank | 29.17% | Increased | Q1 profit ₹1,037 cr, +72% |
| Biocon | 7.52% to 8.16% | +0.64 pp | Biosimilar growth |
| Lenskart Solutions | More than doubled | Sharp rise | Post-IPO visibility |
| Piramal Pharma | Down 17.7 pp | Sharp cut | Largest FII exit |
| RBL Bank | Down 11.4 pp | Sharp cut | Exposure trimmed |
| Financials (sector) | 14.3% to 14.8% | +0.5 pp | Selective lender buying |
DII Holding Changes: Where Are Mutual Funds Doubling Down?
Screen: DII shareholding trends through June 2026, per Elara Securities and Business Standard.
| Stock / Index | Earlier DII Stake | Latest DII Stake | Trend |
|---|---|---|---|
| PNB Housing Finance | 6.88% (Mar 2024) | 44.1% (Mar 2026) | +37.2 pp |
| Nifty 50 aggregate | 20.7% (Sep 2023) | 25.5% (Jun 2026) | +4.8 pp |
| NSE 500 aggregate | 16.8% (Sep 2023) | 20.0% (Jun 2026) | +3.2 pp |
| Eternal, ITC, Dr Reddy’s, Tata Consumer | Eight quarters | Raised every quarter | Consistent buying |
| IndusInd Bank (mutual funds) | 27.55% | 25.36% | -2.19 pp |
Upcoming Dividends: Which Record Dates Should Income Investors Mark?
Screen: fixed record dates and declared payouts awaiting payment.
| Company | Dividend | Record / Key Date | Status |
|---|---|---|---|
| Steel Authority of India | ₹2.35 final (FY26) | Record date 30 Sep 2026 | Buy before ex-date |
| TCS (CMP ₹2,082) | Second interim (FY27) | Board 8 Oct; record 14 Oct | Amount set by board |
| ONGC (CMP ₹235.86) | ₹1.00 | Payment 30 Sep 2026 | Record date passed |
| Coal India | ₹5.25 paid 4 Sep | Quarterly payer | Trailing ₹26.50 |
| Power Grid (CMP ₹269.40) | ₹1.25 paid 13 Aug | Semi-annual payer | Trailing ₹9.00 |
Long-Term Buys: Which Stocks Have a Multi-Year Runway?
Screen: brokerage Buy ratings or strong three-year profit growth with clean balance sheets.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Pearl Global Industries | 1,353 (Fri high) | +6.12% | FY28E revenue ₹6,930 cr | EBITDA CAGR 32% |
| Indegene | 608.95 | 2.13% below high | PAT growth 27% | Margin expansion |
| Welspun Corp | 2,832.40 | 0.18% below high | OCF ₹3,204.28 cr | Sales +25% a year |
| HDFC AMC | 2,377.00 | Zero debt | 3-yr profit CAGR 26.2% | SIP beneficiary |
| Persistent Systems | 5,380.00 | Zero debt | 3-yr profit CAGR 26.5% | IT growth leader |
High Dividend Yield Stocks: Where Is the Income Highest?
Screen: trailing 12-month dividend divided by the latest verified price.
| Stock | Price ₹ (date) | Trailing Dividend ₹ | Yield |
|---|---|---|---|
| Coal India | 424.80 (25 Sep) | 26.50 | 6.24% |
| ONGC | 235.86 (25 Sep) | 13.25 | 5.62% |
| Petronet LNG | 285.50 (25 Sep) | 10.00 | 3.50% |
| Power Grid Corporation | 269.40 (25 Sep) | 9.00 | 3.34% |
| Hindustan Zinc | 561.90 (14 Aug) | 11.00 | 1.96% |
Fundamentally Strong Stocks: Which Balance Sheets Look Bulletproof?
Screen: zero or negligible debt, superior returns and steady profit growth.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Zydus Lifesciences | 1,203.90 | +2.00% | ROE 19.69%, ROCE 21.39% | P/E below industry |
| Oracle Financial Services | 10,758.00 | Zero debt | Profit CAGR 13.5% | P/E 27.4 |
| ICICI Lombard General | 1,554.00 | Zero debt | Profit CAGR 17.0% | P/E 32.0 |
| Tata Elxsi | 3,186.90 | Zero debt | ROE 36.00%, ROCE 52.73% | Elite returns |
| Abbott India | 26,935.80 | Zero debt | Profit CAGR 17.8% | Defensive pharma |
Low Debt Mid Caps: Which Mid-Sized Companies Carry No Borrowings?
Screen: mid caps with zero total debt as of 25 September 2026, per Equitymaster.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Multi Commodity Exchange | 3,325.00 | -3.00% | Profit CAGR 107.5% | P/E 54.8 |
| NALCO | 358.50 | Zero debt | Profit CAGR 59.3% | P/E 9.7 |
| Nippon Life India AMC | 1,156.00 | Zero debt | Profit CAGR 28.3% | P/E 45.2 |
| Havells India | 1,095.00 | Zero debt | Profit CAGR 16.4% | P/E 42.9 |
| Supreme Industries | 3,544.00 | +3.38% | P/E 51.0 | Piping leader |
Cash-Rich Small Caps: Which Smaller Firms Run Debt-Free?
Screen: small caps with zero borrowings as of 25 September 2026, per Dhan.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Force Motors | 17,388.00 | Zero debt | ROCE 33.80% | P/E 18.26 |
| Garware Hi-Tech Films | 6,640.00 | Zero debt | ROCE 16.71% | P/E 39.62 |
| LMW | 17,133.00 | Zero debt | ROE 13.82% | P/E 104.73 |
| Maharashtra Scooters | 13,052.00 | Zero debt | M-cap ₹14,917 cr | Holding company |
| New India Assurance | 176.60 | Zero debt | M-cap ₹29,104 cr | IRDAI rules risk |
Volume Shockers: Where Did Trading Activity Explode?
Screen: multiple of average volume, HDFC Sky midday snapshot, 25 September.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Transport Corp of India | 942.85 | +13.13% | 82.79x volume | Buyback plan |
| Heranba Industries | 193.69 | +12.43% | 73.94x volume | Agrochemical demand |
| Som Distilleries | 74.83 | +11.29% | 61.55x volume | 1.52 crore shares |
| Artemis Medicare | 358.30 | +7.69% | 48.75x volume | Healthcare momentum |
| Blue Cloud Softech | 23.33 | +16.30% | 40.59x volume | 4.36 crore shares |
52-Week Highs: Who Is Leading Despite the Slide?
Screen: touched a 52-week high on 25 September; NSE recorded 90 such stocks.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Multi Commodity Exchange | 3,325.00 | -3.00% | High ₹3,481.40 | Profit booking |
| Zydus Lifesciences | 1,203.90 | +2.00% | High ₹1,208.60 | M-cap over ₹1.15 lakh cr |
| Welspun Corp | 2,832.40 | 0.18% below high | High ₹2,837.50 | Up from ₹709.75 low |
| Engineers India | 315.65 | +6.40% | High ₹318.90 | Order momentum |
| SPR Auto Technologies | 4,746.80 | 0.89% below high | High ₹4,789.10 | Auto parts strength |
52-Week Lows: Which Big Names Are Hitting Rock Bottom?
Screen: touched a 52-week low on 25 September; NSE recorded 120 such stocks.
| Stock | CMP ₹ | Change / Gap | Key Metric | Why It Qualifies |
|---|---|---|---|---|
| Hindustan Unilever | 1,942.90 | 1.43% above low | Low ₹1,915.50 | FMCG de-rating |
| Wipro | 164.02 | 1.46% above low | Low ₹161.66 | 1-yr return -32.22% |
| Britannia Industries | 4,937.50 | 1.12% above low | Low ₹4,883.00 | Staples weakness |
| Tata Consumer Products | 983.20 | -0.31% | Low ₹979.20 | 1-yr return -12.79% |
| GIC Re | 337.50 | 0.36% above low | Low ₹336.30 | P/E 7.0, zero debt |
Sector Performance India 2026: Which Sectors Are Leading and Which Are Sinking?
Index data are from NSE as of market close, 25 September 2026. Earnings trends are Q1 FY27 aggregates compiled by Bajaj Broking.
| Sectoral Index | Close | Day % | 1-Month % | Latest Quarter Earnings Trend | Outlook |
|---|---|---|---|---|---|
| Nifty IT | 28,160.90 | -0.17% | -8.48% | Index -18.49% in a year | Weak |
| Bank Nifty | 55,580.40 | +0.26% | -3.36% | Bank profit +27.8% | Positive |
| Nifty PSU Bank | 8,294.50 | +0.28% | -3.59% | Index +12.19% in a year | Neutral |
| Nifty Pharma | 27,003.00 | -0.10% | +1.65% | Sector profit -27.1% | Positive |
| Nifty FMCG | 45,941.30 | +0.40% | -3.70% | Index -16.63% in a year | Weak |
| Nifty Auto | 26,967.90 | +0.89% | -7.70% | Auto sales +44.0% | Mixed |
| Nifty Metal | 13,087.15 | +0.35% | -2.13% | Non-ferrous profit +144.9% | Positive |
| Nifty Energy | 37,440.35 | +0.21% | -2.27% | Oil profit -91.3% | Weak |
| Nifty Realty | 869.35 | +0.92% | -5.28% | Realty sales +56.0% | Volatile |
Leaders and laggards: pharma is the only major index up over the month, helped by about ₹15,800 crore of FPI inflows into healthcare since July, and metals lead over one year with a 29.80% gain. IT is down 8.48% in a month as US yields squeeze tech budgets, while FMCG and autos show a valuation reset rather than an earnings collapse.
Top 10 Gainers and Top 10 Losers: Who Won and Lost on the Nifty 50?
The top five in each table use NSE closing data; rows six to ten use percentage moves reported to one decimal, so their rupee changes are approximate.
Nifty 50 Top 10 Gainers (25 September 2026)
| Stock | Close ₹ | Change ₹ | Change % | Reason for Move |
|---|---|---|---|---|
| Axis Bank | 1,222.40 | +35.95 | +3.03% | Private bank value buying |
| Asian Paints | 2,444.00 | +51.21 | +2.14% | Softer crude; double bottom |
| Mahindra and Mahindra | 3,035.00 | +52.20 | +1.75% | Rebound from support |
| Bajaj Finance | 996.90 | +14.93 | +1.52% | NBFC strength |
| HCL Technologies | 1,258.00 | +14.43 | +1.16% | IT bargain hunting |
| InterGlobe Aviation | 4,948.00 | approx. +58.7 | +1.2% | Brent fell 2.1% |
| Power Grid Corporation | 269.40 | approx. +2.9 | +1.1% | Defensive buying |
| UltraTech Cement | 11,156.00 | approx. +99.5 | +0.9% | Infra demand |
| HDFC Bank | 735.40 | approx. +6.6 | +0.9% | Heavyweight support |
| Bajaj Auto | 11,305.00 | approx. +100.8 | +0.9% | Auto index led |
Nifty 50 Top 10 Losers (25 September 2026)
| Stock | Close ₹ | Change ₹ | Change % | Reason for Move |
|---|---|---|---|---|
| Max Healthcare Institute | 1,014.00 | -32.01 | -3.06% | Hospital profit booking |
| Tata Motors PV | 290.45 | -4.54 | -1.54% | Weak car demand |
| Infosys | 1,000.20 | -14.30 | -1.41% | US yield worries |
| ONGC | 235.86 | -3.13 | -1.31% | Lower crude realisations |
| Trent | 2,669.30 | -30.78 | -1.14% | Retail weakness |
| SBI Life Insurance | 1,742.00 | approx. -12.3 | -0.7% | IRDAI overhang |
| ICICI Bank | 1,326.80 | approx. -8.0 | -0.6% | Insurance-income caution |
| Bharti Airtel | 1,785.40 | approx. -10.8 | -0.6% | Weekly laggard |
| Hindalco Industries | 977.00 | approx. -4.9 | -0.5% | Post-rally profit booking |
| Tata Consumer Products | 983.20 | -3.10 | -0.31% | 52-week low |
Stock Recommendations for Today: Which Trades Offer the Best Risk-Reward?
Levels marked desk are Dailyfinancial calculations targeting at least twice the risk; named analyst levels are credited.
Mahindra and Mahindra (M&M)
- CMP and trigger: ₹3,035; rebound from the ₹2,896 to ₹2,900 base after a slide from ₹3,550.
- Entry / Target / Stop: ₹3,000 to ₹3,035 / ₹3,315 (desk) / ₹2,895 (Sumeet Bagadia, Choice Broking).
- Time frame: two to four weeks.
- Rationale: rural jobs and record GST collections support tractors and SUVs.
- Key risk: the auto index is down 7.70% in a month.
Asian Paints
- CMP and trigger: ₹2,444; double bottom at ₹2,390 to ₹2,400 with a reversal candle.
- Entry / Target / Stop: ₹2,420 to ₹2,444 / ₹2,490 then ₹2,540 (desk) / ₹2,390.
- Time frame: one to three weeks.
- Rationale: cooler crude eases raw material costs.
- Key risk: Brent back above $105 could stall the move.
HCL Technologies
- CMP and trigger: ₹1,258; base formation below its moving-average cluster.
- Entry / Target / Stop: ₹1,240 to ₹1,258 / ₹1,374 (desk) / ₹1,200 (Sumeet Bagadia).
- Time frame: three to six weeks.
- Rationale: record Nasdaq close; Q2 results start mid-October.
- Key risk: US 10-year yield breaking above 5.2%.
Axis Bank
- CMP and trigger: ₹1,222.40; top Nifty gainer on 69.2 lakh shares traded.
- Entry / Target / Stop: ₹1,200 to ₹1,222 / ₹1,305 (desk) / ₹1,180.
- Time frame: two to four weeks.
- Rationale: bank profits rose 27.8% in Q1 FY27.
- Key risk: IRDAI rules could dent bancassurance fees.
Pearl Global Industries
- CMP and trigger: ₹1,353 Friday high; MOFSL reiterated Buy after an analyst meet.
- Entry / Target / Stop: ₹1,300 to ₹1,350 / ₹1,500 (MOFSL) / ₹1,230 (desk).
- Time frame: 6 to 12 months.
- Rationale: MOFSL sees PAT growing 38% a year over FY26 to FY28.
- Key risk: US tariffs on textile exports.
Portfolio Suggestions by Risk Appetite: How Should You Position Now?
Conservative Portfolio: Income and Capital Protection First
| Stock | Allocation % | Sector | Recent Earnings Driver |
|---|---|---|---|
| Coal India | 20% | Mining / Energy | Yield 6.24% |
| Power Grid Corporation | 20% | Utilities | Yield 3.34% |
| HDFC Bank | 20% | Private Bank | Bank profit +27.8% |
| ICICI Lombard General | 15% | Insurance | Profit CAGR 17.0% |
| Zydus Lifesciences | 15% | Pharma | ROE 19.69% |
| Petronet LNG | 10% | Gas Utility | Yield 3.50% |
- Pros: dividend cushion, low debt, defensive sectors.
- Cons: limited upside in a sharp rally; PSU payouts depend on policy.
Moderate Portfolio: Balanced Growth With a Safety Net
| Stock | Allocation % | Sector | Recent Earnings Driver |
|---|---|---|---|
| Axis Bank | 20% | Private Bank | Bank profit +27.8% |
| Mahindra and Mahindra | 15% | Auto | Rural demand |
| HCL Technologies | 15% | IT | Q2 results mid-Oct |
| HDFC AMC | 15% | Asset Management | Profit CAGR 26.2% |
| Asian Paints | 10% | Consumer | Crude relief |
| Coal India | 15% | Mining / Energy | Yield 6.24% |
| Oracle Financial Services | 10% | IT Products | P/E 27.4 |
- Pros: mixes recovery plays, income and quality across six sectors.
- Cons: IT and banks stay exposed to US yields and IRDAI rules.
Aggressive Portfolio: Higher Risk for Higher Potential Reward
| Stock | Allocation % | Sector | Recent Earnings Driver |
|---|---|---|---|
| Welspun Corp | 20% | Steel Pipes | Q1 PAT +198.6% |
| Pearl Global Industries | 15% | Textiles | PAT CAGR 38% |
| Indegene | 15% | Life Sciences Tech | MOFSL target ₹708 |
| Multi Commodity Exchange | 15% | Capital Markets | Profit CAGR 107.5% |
| NALCO | 15% | Metals | P/E 9.7 |
| Force Motors | 10% | Auto | ROCE 33.80% |
| Engineers India | 10% | Engineering Services | Dangote refinery mandate |
- Pros: strongest earnings momentum and 52-week-high leaders.
- Cons: higher volatility and deeper drawdowns if Nifty breaks 22,700.
Final Thought: What Should Investors Remember From This Seven-Week Slide?
Key Takeaways
- Nifty 50 down 3.90% and Sensex 3.98% in September, driven by crude above $100 and US yields at 2007 highs.
- Fundamentals hold: GDP +7.8%, unemployment 5.0%, GST +14.8%.
- CPI at 4.82% and a Fed hike keep the RBI on hold at 5.25%.
- DIIs absorbed FII selling; their Nifty 50 ownership is 25.5%.
- 23,000 is the line in the sand.
Three unique data points stand out. Pharma sits 0.9% from its high while IT is 30.1% below its peak. On a day the Nifty rose, 120 NSE stocks hit 52-week lows against 90 at highs, so the rally was narrow. And excluding jewellery, CPI inflation was about 4.16%, softer than the headline suggests.
For the session ahead, watch three things: whether the Nifty holds 23,000 into Tuesday’s weekly expiry, whether Brent stays above $105 after the rejected Iran proposal, and whether FII selling slows. A close above 23,370 would be the first real sign the seven-week slide is ending.
Frequently Asked Questions About the Indian Stock Market Today
Why is the Indian stock market falling in September 2026?
The fall is driven mainly by global factors. Brent crude has stayed above $100 a barrel, the US 10-year yield reached its highest since 2007, the Fed raised rates, and FIIs sold ₹17,131 crore this month. IRDAI’s commission-cap proposal also hit financial stocks on 24 September.
What was the Sensex and Nifty closing on Friday, 25 September 2026?
The BSE Sensex closed at 73,895.74, up 315.20 points or 0.43%. The NSE Nifty 50 closed at 23,140.50, up 77.40 points or 0.34%. Bank Nifty ended at 55,580.40, up 0.26%, and India VIX fell 4% to 12.18. Despite the bounce, both benchmarks recorded a seventh straight weekly loss.
Will Nifty go up or down on 28 September 2026?
Early signals point to a softer start. GIFT Nifty traded about 69 to 77 points lower near 23,110 on Monday morning as Asian markets fell and crude rose. The key support is 23,000, and resistance sits at 23,200 to 23,370.
What is the current RBI repo rate in 2026?
The RBI repo rate is 5.25%. The Monetary Policy Committee held it unchanged on 5 August 2026 with a neutral stance, its fourth straight pause. The Standing Deposit Facility is 5.00% and the Marginal Standing Facility is 5.50%, and rising inflation makes a near-term cut unlikely.
What is India’s latest CPI inflation rate?
India’s CPI inflation was 4.82% in August 2026, up from 4.45% in July, according to MoSPI. Rural inflation was 5.23% and urban 4.31%. Excluding jewellery, inflation was about 4.16%. The September figure is scheduled for release on 12 October 2026.
What is India’s GDP growth rate for Q1 FY27?
India’s real GDP grew 7.8% in April to June 2026, beating the RBI’s 7% estimate. Manufacturing grew 9.2% and services 10%. The RBI expects full-year FY27 growth of 6.7%, while CareEdge Ratings projects 7.3%, keeping India among the fastest-growing major economies.
Is the stock market open during the bank strike on 28 September 2026?
Yes. NSE and BSE are open on Monday, 28 September, with normal trading hours from 9:15 AM to 3:30 PM. The three-day bank strike from 28 to 30 September may affect some branch services, but it is not an exchange holiday.
Is this a good time to buy Indian stocks?
For long-term investors, staggered buying in quality companies can make sense while valuations cool; the Nifty trades at a P/E of 19.56, near its long-run average of about 20. Short-term traders should wait for a close above 23,370 before turning aggressive.
Disclaimer: This content is for educational and informational purposes only and is not investment advice or a recommendation to buy or sell any security. Market data are as of market close on 25 September 2026 and pre-open cues on 28 September 2026, and may change. Please consult a SEBI-registered investment adviser before making any investment decision. Dailyfinancial.in and its writers may or may not hold positions in the stocks discussed.