Family Floater vs Individual Health Insurance — Which Costs Less, and When Does One Shared Pool Become a Risk?
A family floater can cost far less than separate policies for a young family, but one serious illness can drain the shared cover for everyone. Here is how to weigh price against protection, with premium examples and the maths of an exhausted pool.
A couple in their early thirties with a toddler sits down to buy health insurance. One option is a single ₹10 lakh family floater; the other is three separate ₹10 lakh policies. The floater costs roughly half as much, and the choice looks obvious. Ten years later, one parent is diagnosed with cancer, the claim eats most of the shared pool, and the child is hospitalised the same year. The cheap option suddenly does not look so cheap.
The floater-versus-individual decision is not really about which product is better. It is about how many people share how much money, how likely they are to claim at the same time, and how that changes as the family ages. This guide puts numbers on each of those questions and ends with a simple framework for deciding, and re-deciding, as your family grows.
Two Ways to Share the Same Rupee
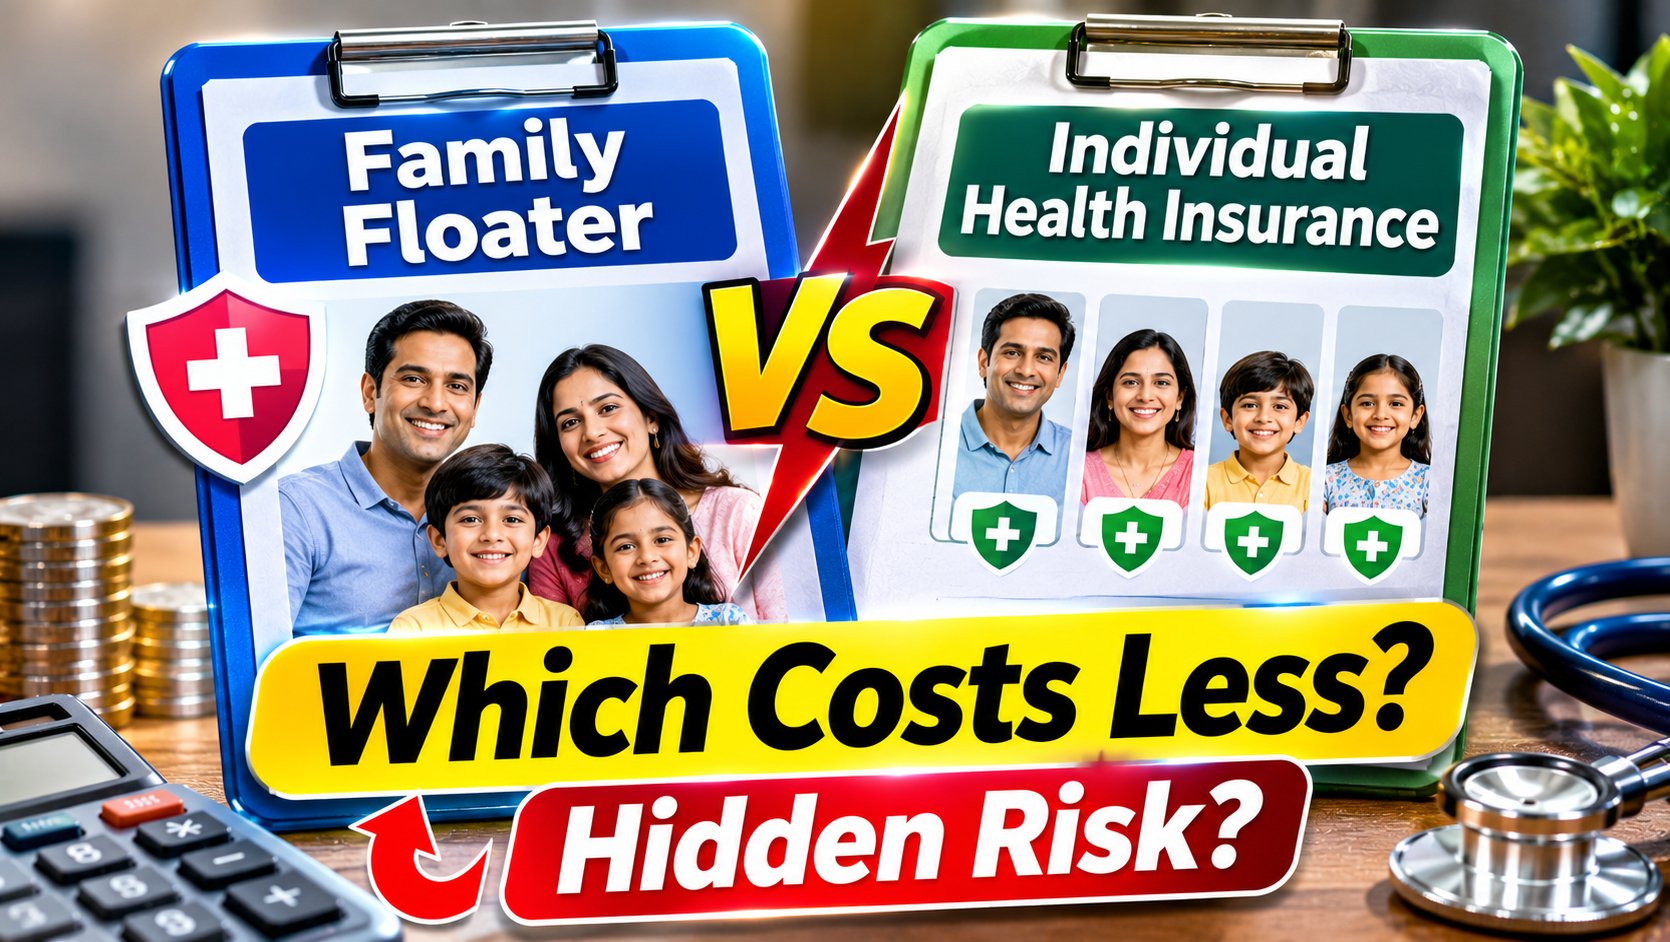
An individual policy gives each person their own sum insured. A family floater gives everyone one shared pool: any member can use all of it, but every rupee one person claims reduces what is left for the others until the policy renews. The premium for a floater is calculated on the age of the oldest member, Nyvo’s guide notes, so adding an older person raises the price for everyone on it.
Family floater
- One sum insured shared by all members
- One premium, priced on the eldest member’s age
- Usually cheaper for young, healthy families
- One big claim can leave little for the rest
- Single renewal date, single set of documents
Individual policies
- Each member has a separate sum insured
- Premium priced on each person’s own age
- Costs more in total for a young family
- One member’s claim does not touch another’s cover
- Each policy continues independently if the family splits
Business Standard’s December 2025 survey of insurance experts found broad agreement on the trade-off. Policybazaar’s Siddharth Singhal described floaters as suited to families in their late 20s and 30s, while people in their 40s and 50s with chronic conditions “must choose individual plans to avoid exhausting the family pool.” Universal Sompo’s Arti Mulik warned that “a single large hospital bill can exhaust the entire shared pool.”
The Price Gap, in Real Quotes
Premiums vary by insurer, city, age and health, so treat the figures below as indicative. They come from Nyvo’s comparison pages, updated in March and October 2026, and are not tied to a single plan unless named.
The saving, worked out (our calculation from the midpoints): for a couple and two children, a floater at about ₹20,000 against four policies at about ₹55,000 saves ₹35,000 a year, or about 64%. For a couple and one child, about ₹14,000 against ₹25,000 saves ₹11,000, or 44%. The more young members share one pool, the larger the discount, because a floater’s price rises far less than proportionally with each added child.
What Happens When One Claim Eats the Pool
The floater’s weakness shows up in a bad year. Care Health Insurance’s claims data, reported by Business Today in February 2026, puts early-stage cancer treatment at ₹5 lakh to ₹7 lakh per case and advanced cases at ₹20 lakh to ₹30 lakh. A single serious illness can consume most of a ₹10 lakh floater, leaving the rest of the family exposed until renewal.
Under four individual ₹10 lakh policies, the same year would have been fully covered: the parent’s ₹7 lakh claim would touch only that parent’s policy, and every other member would still have their full ₹10 lakh. That is the protection you buy with the higher premium.
Seen this way, the extra premium for individual policies is the price of independence between family members. Whether it is worth paying depends on how likely two serious claims in one year are for your family, which rises with age and with existing illness.
What families often get wrong: they treat the restoration benefit as a guarantee that the floater “refills”. Many restoration features apply only after the sum insured is fully used, may not cover a second claim for the same illness, and in some plans cannot be used by the same member. If restoration is your safety net, read exactly when it triggers before relying on it.
The Fine Print That Decides Real Value
No-claim bonus works against floaters in busy years
Most retail health plans increase your sum insured for each claim-free year, a cumulative or no-claim bonus. The size and cap vary by plan. In a floater, a claim by any one member typically affects the bonus for the whole policy, so a family with young children, who visit hospitals more often, may rarely build up a bonus. With individual policies, a healthy adult who never claims keeps growing their own cover even if a child claims every year.
Restoration is not a second sum insured
Restoration refills the sum insured after it is used, but on the insurer’s terms. Some plans restore only after the base cover is fully exhausted; some exclude a second claim for the same illness; some allow restoration only for other members. Over a decade, these details can matter more than a few thousand rupees of premium, which is why comparing the policy wording is as important as comparing the price.
Adding a Super Top-Up to Either Structure
Whichever structure you choose, a super top-up is the cheapest way to protect against the very large bills that cause floater exhaustion. It pays once the family’s total claims in a year cross a set deductible, usually matched to your base cover.
Illustration (our calculation): a family holds a ₹10 lakh floater and a ₹25 lakh super top-up with a ₹10 lakh deductible. One member needs advanced cancer care costing ₹25 lakh, within Care Health’s ₹20 lakh to ₹30 lakh range. The floater pays the first ₹10 lakh and the super top-up pays the remaining ₹15 lakh. If a child is then admitted for ₹2 lakh in the same year, the deductible has already been crossed, so the top-up pays that too, up to its remaining ₹10 lakh.
The super top-up does not fix every floater weakness. It does not help in a year of many small claims that stay below the deductible, and it adds its own waiting periods. But it turns the “one big claim drains the pool” problem into a manageable one, at a fraction of the cost of raising the base cover by the same amount.
Every Feature, Floater vs Individual
| Feature | Family floater | Individual policy | What it means for you |
|---|---|---|---|
| Sum insured | Shared by all members | Separate for each person | Floater risks exhaustion in a bad year |
| Premium basis | Eldest member’s age | Each member’s own age | Older members make floaters expensive |
| Cost for young families | Lower, often 40% to 65% less | Higher in total | Floater wins on price early on |
| No-claim bonus | Lost for all if anyone claims | Kept by members who do not claim | Individual plans reward healthy members |
| Children turning adults | May need to move out at a plan’s age limit | Own policy continues | Check the floater’s maximum dependent age |
| Separation or divorce | Policy must be split | Each continues unchanged | Individual is simpler when lives diverge |
| Tax under old regime | Section 80D on premium paid | Section 80D on premiums paid | Same limit: up to ₹25,000 for self and family |
Which Structure Fits Which Family
The table below is a decision guide built from the expert views reported by Business Standard and the cost data above. It is indicative, not a rule.
| Family profile | Typical ages | Suggested structure | Why | Watch out for |
|---|---|---|---|---|
| Young couple, no children | 25 to 32 | Floater, ₹10 lakh or more | Lowest cost; similar risk profiles | Plan to add a super top-up as income grows |
| Couple with young children | 28 to 38 | Floater plus super top-up | Cheap per member; top-up covers large bills | Restoration terms; maternity waiting periods |
| One adult with a chronic condition | 35 to 50 | Individual for that adult; floater for others | Protects the family pool from repeated claims | Pre-existing disease waiting period |
| Adults in their 40s and 50s | 40 to 55 | Individual policies | Higher claim risk, avoids shared exhaustion | Higher premiums each year with age |
| Parents over 60 | 60 and above | Separate senior policy for parents | Keeps your floater priced on your age | Co-pays and room-rent caps on senior plans |
| Single earner, single person | Any | Individual policy | No one to share a pool with | Buy early to finish waiting periods |
Why adding parents to your floater is usually a mistake
Because a floater’s premium follows the oldest member, adding a 62-year-old parent to a policy for a 32-year-old couple prices the whole family as if everyone were 62. It also puts the people most likely to claim into the same pool as your children. A separate senior policy for parents keeps your floater cheap and your children’s cover intact.
The Hybrid Most Families End Up With
In practice, the choice is rarely all floater or all individual. A common structure, consistent with the expert views reported by Business Standard, mixes both. Consider a family with a 36-year-old husband, a 34-year-old wife who has been diagnosed with diabetes, two children aged 6 and 3, and the husband’s parents aged 64 and 61.
- Floater for the husband and both children: healthy members share one pool priced on a 36-year-old.
- Individual policy for the wife: her diabetes-related claims cannot drain the children’s cover, and she builds her own bonus history.
- Separate senior policy for the parents: keeps the family floater from being priced on a 64-year-old.
- One super top-up across the core family: protects against any single large bill.
This costs more than one big floater, but it isolates the highest-risk members from the people they would otherwise compete with for cover. It also makes future changes easier: when the children grow up, they can move to their own policies without disturbing anyone else’s cover.
When children grow up
Floaters usually allow dependent children up to a maximum age set by the insurer. When a child crosses it, or starts working, they typically need to move out to their own policy. Ask whether the insurer lets them carry forward waiting-period credits when they do, so a young adult does not start fresh waiting periods just as they leave home.
How the Right Choice Shifts as Your Family Ages
A structure that is right at 30 may be wrong at 45. The stages below are indicative.
- Ages 25 to 32Start with a floater for the couple; ₹10 lakh base cover.
- Ages 30 to 40Add children; layer a super top-up of ₹20 lakh or more.
- Ages 40 to 50Move higher-risk adults to individual plans; keep children on a floater.
- Age 50 and aboveIndividual policies for each adult; children shift to their own cover as they become independent.
Anand Rathi’s Milind Tayde suggested exactly this kind of shift to Business Standard: moving adults to individual policies in their late 30s and 40s while keeping children on a floater, so one person’s frequent or high-value claims do not erode shared cover. The key is to review the structure at each renewal rather than renewing on autopilot.
Before You Sign: A Practical Checklist
- List every family member with age and any existing health condition.
- Get live quotes for both a floater and individual policies; compare total annual cost.
- Check how the floater’s restoration benefit triggers and whether it applies to the same person or illness.
- Confirm the maximum age at which children can remain on a floater.
- Add a super top-up to raise total cover cheaply, whichever structure you choose.
Questions Families Are Asking
Which is better, family floater or individual health insurance?
A floater is usually better value for young, healthy families. Individual policies are better when members are older, have chronic conditions or are at different life stages, because one person’s claims cannot drain another’s cover.
How is a family floater premium calculated?
Mainly on the age of the oldest member covered, along with sum insured, city, plan and number of members. Adding an older person raises the premium for the whole policy.
How much does a ₹10 lakh family floater cost?
Indicative quotes from Nyvo put it at ₹12,000 to ₹16,000 a year for a couple aged 30 with one child and ₹18,000 to ₹22,000 with two children in a Tier-1 city. Live quotes vary.
Should I add my parents to my family floater?
Usually not. Their age raises the premium for everyone, and their higher claim risk can exhaust the pool. A separate senior citizen policy for parents is generally better.
What happens if one member uses the entire floater sum insured?
Other members have no cover left until renewal, unless the plan has a restoration benefit that refills the sum insured. Check exactly when restoration applies.
Can I convert a family floater into individual policies later?
Many insurers allow members to split into individual policies at renewal while keeping waiting-period credits, subject to the insurer’s terms. Ask your insurer before renewal.
Is a family floater eligible for tax benefits?
Yes, under the old tax regime. Section 80D allows up to ₹25,000 a year for self, spouse and children, and a further amount for parents. The new regime does not allow this deduction.
Does a no-claim bonus work differently in a floater?
Yes. In a floater, a claim by any member usually affects the bonus for the whole policy. With individual policies, members who do not claim keep their own bonus.
The Short Version
A family floater shares one sum insured across the family and is priced on the eldest member’s age. For young, healthy families it can cost 40% to 65% less than separate policies. Its weakness is a bad year: one serious illness can drain the pool for everyone. Use a floater for young members, individual cover for older or chronically ill adults and a separate policy for parents, add a super top-up for large bills, and review the structure at every renewal.