India Is Still Filling Its SIP Tank — When Will SWPs Matter, and How Long Can ₹1 Crore Pay You?
India Is Still Filling Its SIP Tank — When Will SWPs Matter, and How Long Can ₹1 Crore Pay You?
Carnelian Asset Management founder Vikas Khemani says India is in its SIP accumulation phase and SWPs may gain relevance over 25 years. Here is what AMFI data, ageing projections and withdrawal maths say about that shift.
Every month, more than ten crore SIP accounts quietly pour money into Indian mutual funds. In September 2026 that stream reached a record ₹32,490 crore. Almost all of it is money going in. Very little of India’s mutual fund conversation is about the harder question that arrives later: how do you turn a pile of units into a monthly income that does not run dry while you are still alive to need it?
That is the point Vikas Khemani, founder of Carnelian Asset Management, made at the ET Wealth Expo, as reported in a headline carried by inkl: India is still in the SIP accumulation phase, and systematic withdrawal plans may gain relevance over the next 25 years. The remark sounds like a footnote. It is actually a forecast about how tens of millions of households will one day live off their savings, and the arithmetic of that second phase is far less forgiving than the first.
The Numbers Behind “Still Accumulating”
AMFI’s September 2026 data, as reported by Angel One, shows how lopsided the industry is towards inflows. SIP assets stood at ₹17.86 lakh crore, or 21.6% of total industry assets of ₹82.64 lakh crore. New SIP registrations of 63.26 lakh outnumbered the 49.68 lakh SIPs that were discontinued or matured, and the stoppage ratio fell for a fifth straight month to 78.53%.
The growth curve explains Khemani’s framing. Data compiled by Factly from AMFI shows annual SIP contributions of ₹43,921 crore in 2016-17, an average of about ₹3,660 crore a month. By 2024-25 the annual figure was roughly ₹2.89 lakh crore, over ₹24,000 crore a month. A large share of today’s SIP money therefore belongs to investors who started within the last eight or nine years. Few of them are anywhere near the point of drawing an income.
Why the stoppage ratio is not a red flag
A stoppage ratio of 78.53% sounds alarming, but it measures SIPs discontinued or completed as a share of new registrations, not of all SIPs. It spiked to 95.46% in May 2026 and has fallen every month since, to 81.05% in August and 78.53% in September. It remains above the 76.27% of September 2025. In plain terms, more SIPs are still being started than stopped, which is what an accumulation phase looks like.
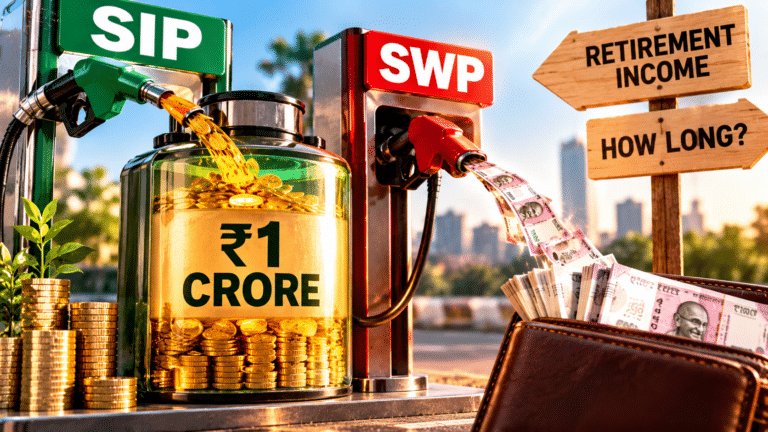
SIP Fills, SWP Drains: Getting the Terms Straight
A systematic investment plan moves a fixed amount from your bank account into a fund on a set date. A systematic withdrawal plan is its mirror image. You hold a lump sum in a fund and instruct the AMC to redeem enough units each month or quarter to pay you a fixed amount. The fund keeps the rest invested. If returns beat withdrawals, the corpus can grow; if not, it shrinks.
SIP: the filling phase
- Buys more units when NAVs fall, averaging costs down
- Market falls are mostly an opportunity
- Time horizon of 15 to 30 years
- Main risk is stopping too early
SWP: the drawing phase
- Sells more units when NAVs fall to pay the same amount
- Market falls early on can do lasting damage
- Time horizon of 20 to 30 years after retirement
- Main risk is outliving the money
The asymmetry in the second bullet matters most. In accumulation, a crash makes your rupee go further. In withdrawal, a crash forces you to sell more units at low prices, and those units are not there to recover when markets bounce. Financial planners call this sequence-of-returns risk, and it is why the SWP phase needs a different playbook rather than simply reversing the SIP.
Why 25 Years Is a Plausible Horizon
Khemani’s 25-year timeline fits India’s demographics. The UNFPA India Ageing Report 2023 counted 149 million people aged 60 or above in July 2022, 10.5% of the population. It projects 347 million, or 20.8%, by 2050. The report also puts life expectancy at 60 at about 18.3 more years for men and 19 for women, which means a retirement corpus must usually last close to two decades and often longer.
Put the two trends side by side. An investor who began a SIP at 30 in 2018 turns 60 in 2048, just as the over-60 population nears its projected peak share. The wave of SIP money that built up after 2017 will reach retirement age in roughly the window Khemani describes.
- 2016-17Annual SIP contributions of ₹43,921 crore, about ₹3,660 crore a month.
- April 1, 2023Gains on new debt fund investments become taxable at slab rates regardless of holding period.
- July 23, 2024Budget sets equity LTCG at 12.5% above ₹1.25 lakh and STCG at 20%.
- 2024-25Annual SIP contributions reach about ₹2.89 lakh crore.
- September 2026Record SIP inflow of ₹32,490 crore; 10.06 crore contributing accounts.
- 2050UNFPA projects 347 million Indians aged 60 or above, 20.8% of the population.
The Payoff From 25 Years of Filling
To see why the withdrawal phase deserves planning, start with what a disciplined SIP can build. The figures below assume ₹10,000 a month and a 12% annual return, which is an illustrative assumption, not a forecast. Equity returns vary widely, and 2026 alone has seen the Nifty fall sharply.
The last five years add more than the first fifteen combined. That is compounding at work, and it is also why the first years of retirement are so dangerous: the corpus is at its largest just as you start selling from it.
How Long Does ₹1 Crore Really Last?
The most common SWP mistake is choosing a withdrawal that looks modest against the corpus while ignoring inflation. ₹60,000 a month from ₹1 crore is a 7.2% annual withdrawal. At an 8% return with the payout fixed, it would last indefinitely on paper. But groceries, medicine and electricity do not stay at today’s prices. Once the withdrawal rises 6% a year to keep pace with inflation, the picture changes sharply.
| Starting monthly SWP | Initial withdrawal rate | Lasts at 7% return | Lasts at 8% return | Lasts at 10% return |
|---|---|---|---|---|
| ₹30,000 | 3.6% | 33.4 years | 41.2 years | Does not run out |
| ₹40,000 | 4.8% | 24.1 years | 27.6 years | 43.2 years |
| ₹50,000 | 6.0% | 18.8 years | 20.8 years | 27.5 years |
| ₹60,000 | 7.2% | 15.4 years | 16.8 years | 20.5 years |
| ₹70,000 | 8.4% | 13.1 years | 14.0 years | 16.4 years |
| ₹80,000 | 9.6% | 11.3 years | 12.1 years | 13.8 years |
The table is our calculation for a ₹1 crore corpus, with the monthly withdrawal increased by 6% each year and a steady annual return. Real returns are not steady, so treat these as the best case for each column. A 60-year-old retiree who expects to live to 85 needs about 25 years of income, and the table suggests that a starting withdrawal much above 4% to 5% leaves little margin.
What people actually get wrong: retirees often pick the SWP amount that matches their current expenses, then compare it with the fund’s past returns. A fund that delivered 12% in the decade you were accumulating tells you little about the next decade, and a fixed rupee payout hides the fact that its real value halves in about 12 years at 6% inflation.
Same average return, opposite outcomes
Sequence-risk test (our calculation): take ₹1 crore and a ₹50,000 monthly SWP rising 6% a year. Run 20 years of returns: two years of minus 15% and eighteen years of plus 12%. Both orders produce the same compound return of about 8.95% a year. If the two bad years come first, the corpus runs out in year 16. If they come last, the investor finishes year 20 with about ₹1.57 crore still invested.
Nothing about the fund changed between those two scenarios. Only the timing did. This is the core reason the SWP phase is not just a SIP in reverse, and why planners use cash buffers and asset mix to blunt bad early years.
The Tax Edge That Makes SWPs Attractive
SWPs earn their reputation largely through tax. Each withdrawal redeems units, and only the gain on those units is taxed, not the whole payout. DSP Mutual Fund’s tax guidance gives a worked example: with units bought at ₹100 and a NAV of ₹130, a ₹26,000 monthly SWP redeems 200 units costing ₹20,000, so only ₹6,000 is a taxable gain. Units are redeemed first-in, first-out, so early withdrawals usually come from the oldest, long-term holdings.
| Income route | What is taxed | Rate | TDS for residents | Tax on ₹26,000 a month, 30% slab, year one |
|---|---|---|---|---|
| Equity fund SWP, held over 12 months | Gain portion only | 12.5% above ₹1.25 lakh a year | Generally none | Nil: ₹72,000 annual gain is under ₹1.25 lakh |
| Equity fund SWP, held 12 months or less | Gain portion only | 20% | Generally none | ₹14,400 on ₹72,000 gain |
| Debt fund SWP, bought after April 1, 2023 | Gain portion only | Slab rate | Generally none | ₹21,600 on ₹72,000 gain |
| IDCW payout from a fund | Entire payout | Slab rate | Above ₹5,000 a year per AMC | ₹93,600 on ₹3.12 lakh |
| Fixed deposit interest | Entire interest | Slab rate | Above bank thresholds | ₹93,600 on ₹3.12 lakh |
The final column is our calculation using DSP’s per-withdrawal example scaled to a year, ignoring cess and surcharge, and assuming no other long-term equity gains that year. The gap is real but narrows over time: as the oldest low-cost units are used up, a larger share of each withdrawal becomes gain.
A Four-Stage Bridge From SIP to SWP
The move from accumulation to withdrawal works best as a gradual handover, not a switch flipped on retirement day. The stages and ranges below are indicative, based on common practitioner approaches rather than any regulation.
- Estimate retirement spending in today’s rupees, then inflate it to your retirement year.
- Use a systematic transfer plan in the final years to move money from equity to safer funds in steps rather than in one go.
- Run the SWP from the buffer fund and refill it from equity only after good years.
- Review the withdrawal rate every year; trim it if markets have fallen sharply in the first five years of retirement.
- Keep the capital gains statement from your AMC for each financial year to report SWP gains correctly in your return.
SWP alone, or SWP with a guaranteed floor?
An SWP is flexible but not guaranteed. Annuities from insurers and government-backed schemes for senior citizens pay a fixed income for life or a set term, but they lock money in and the payouts are generally taxed at slab rates. Many planners therefore suggest splitting the job: use guaranteed products to cover essential monthly bills such as food, utilities and insurance premiums, and use an SWP from a hybrid or equity fund for everything else, including travel, gifts and rising medical costs.
This split changes how a market fall feels. If the basic bills are already covered, a bad year in equities means trimming discretionary spending for a while rather than selling units at the bottom to pay for groceries. It also reduces the pressure to start the SWP at an aggressive rate, which, as the table above shows, is the single biggest factor in how long the corpus lasts.
Before you switch on an SWP
Questions Readers Are Searching For
What is an SWP in mutual funds?
A systematic withdrawal plan lets you redeem a fixed amount from a mutual fund at regular intervals, usually monthly. The AMC sells enough units to pay you, and the remaining units stay invested.
Is SWP better than a fixed deposit for monthly income?
An SWP from an equity or hybrid fund can be more tax-efficient because only the gain is taxed, and it may earn more over long periods. But it carries market risk, while FD income is fixed. Many retirees use both.
How much can I withdraw monthly from ₹1 crore?
Our calculations suggest a starting withdrawal of about ₹40,000 a month, or 4.8% a year, rising 6% annually, lasts 27.6 years at an 8% return. ₹60,000 a month on the same terms lasts about 16.8 years.
How is SWP taxed in India?
Only the capital gain in each withdrawal is taxed. For equity funds held over 12 months, gains above ₹1.25 lakh a year are taxed at 12.5%; within 12 months, at 20%. Debt fund gains on investments made after April 1, 2023 are taxed at slab rates.
When should I start an SWP?
Typically when you need regular income, such as at retirement. Starting an SWP from an equity fund within a year of investing can attract exit loads and short-term tax, so most planners build a buffer first.
Can I run a SIP and an SWP at the same time?
Yes, usually in different funds. Some investors draw income from a debt or hybrid fund while continuing a SIP in equity, though running both in the same fund adds little and complicates tax records.
What happens to an SWP if the market falls?
The fund must sell more units to pay the same amount, which shrinks the corpus faster. A bad first few years can shorten how long the money lasts, which is why a cash buffer and a modest withdrawal rate help.
What does the SIP stoppage ratio mean?
It is SIPs discontinued or completed in a month as a percentage of new registrations. At 78.53% in September 2026, more SIPs were started than stopped.
The Short Version
India’s mutual fund story is still about filling the tank: record SIP inflows, more registrations than closures and ₹17.86 lakh crore in SIP assets. As the post-2017 generation of investors ages and the 60-plus population heads towards 20.8% by 2050, withdrawal planning through SWPs will become central. The maths is unforgiving. Start withdrawals near 4% to 5%, raise them with inflation, keep two to three years of expenses outside equity, and remember that bad early years matter far more than bad late ones.