Canara HSBC Life Global Wealth Plan: How the New Dollar ULIP for NRIs Works — and How It Compares With Rivals
Canara HSBC Life Global Wealth Plan: How the New Dollar ULIP for NRIs Works — and How It Compares With Rivals
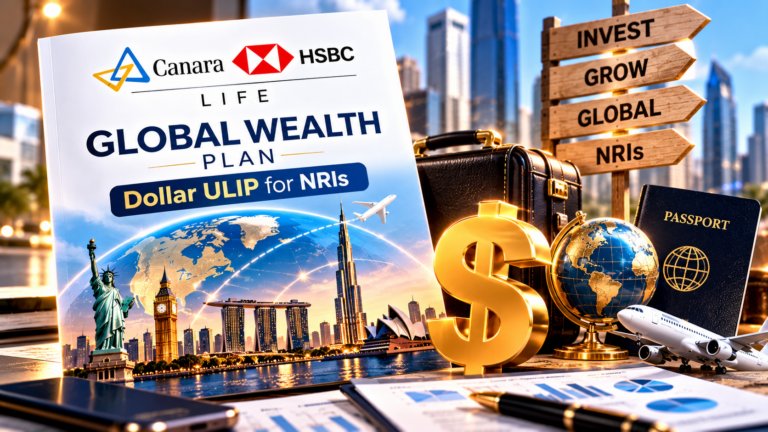
Canara HSBC Life Insurance has launched Global Wealth Plan, a US dollar unit-linked life insurance plan offered from GIFT City and distributed through Policybazaar. Aimed at non-resident Indians, it invests in global equities, gold, silver and debt funds, with three plan options.
October 2026 has become dollar month for Indian life insurers. Within three weeks, Ageas Federal Life, Canara HSBC Life and Bajaj Life have each launched market-linked policies from GIFT City that take premiums in foreign currency and invest globally. For an NRI in the Gulf, Singapore or the United States, the choice of where to put long-term dollar savings with life cover attached has suddenly widened.
Canara HSBC Life’s entry, Global Wealth Plan, stands out for one feature in particular: an option under which the insurer keeps paying your premiums if you die, so your family’s savings plan reaches maturity anyway. Here is how the plan works, what has and has not been disclosed, how it compares with the other two launches, and the numbers an NRI buyer should check.
Quick Summary
Global Wealth Plan is a US dollar ULIP from GIFT City for NRIs, sold through Policybazaar, with three options: Wealth, Wealth Plus and Wealth Forever. Money can go into global equities, gold and silver, and debt funds. Canara HSBC Life says there are no allocation or administration charges, and loyalty additions and maturity boosters apply depending on the option. Wealth Plus pays the sum assured on death and then funds all future premiums so the policy runs to maturity; Wealth Forever gives whole life cover for legacy planning. Minimum premiums, fund charges, policy terms and withdrawal rules were not in the launch material.
What We Know
- Global Wealth Plan, UIN 2026L002V01, is an individual, unit-linked, non-participating life insurance savings plan.
- It is offered from GIFT City in US dollars and distributed through Policybazaar.
- Fund choices cover global equities, gold and silver, and debt.
- Wealth Plus pays the sum assured on death and funds all future premiums until maturity.
- There are no allocation or administration charges, according to Canara HSBC Life.
What Is Still Unclear
- Minimum premium, sum assured multiple, policy terms and entry ages.
- Fund management and mortality charges, and the named funds.
- Partial withdrawal and surrender rules.
- Whether resident Indians can buy it; the launch targets NRIs.
Inside Global Wealth Plan: Three Ways to Use One Policy
The launch press release, dated 19 October 2026, describes Global Wealth Plan as an individual, unit-linked, non-participating life insurance savings plan. In plain terms: part of what you pay buys life cover, the rest is invested in funds you choose, and the policy’s value moves with those funds. There is no share in insurer profits and no guaranteed return unless a specific benefit says so, as Angel One’s report notes.
Wealth: growth first
The Wealth option is built for long-term wealth creation with life cover alongside. It is the closest to a standard ULIP and suits someone who already has adequate term insurance and wants dollar investment exposure.
Wealth Plus: the premium-funding safety net
Wealth Plus adds what Canara HSBC Life calls a Goal Protection Benefit. If the life assured dies during the term, the sum assured is paid immediately, and the insurer then funds all future premiums so the policy continues to maturity. A family saving for a child’s overseas education would receive the lump sum straight away and still get the full fund value at the end of the term.
Wealth Forever: cover for life
Wealth Forever offers whole life cover, aimed at legacy creation and wealth transfer. It suits buyers who want dollar assets to pass to the next generation rather than to fund a specific goal.
What buyers often get wrong
Some coverage has described Wealth Plus as continuing premiums “even if the policyholder stops paying”. That is not what the launch release says. The insurer funds future premiums after the death of the life assured. If you simply stop paying, the usual discontinuance rules of the policy apply, so check them in the brochure.
What Wealth Plus Could Be Worth to a Family
Canara HSBC Life has not published a benefit illustration. To show how the premium-funding benefit works, consider a hypothetical policy with a $5,000 annual premium, a 15-year term and a sum assured of $50,000, ten times the premium. Assume the funds earn 7% a year before charges, and the life assured dies after paying five premiums.
In this illustration, a family under Wealth Plus would receive $50,000 immediately and, because the insurer pays the remaining ten premiums, a fund of about $134,440 at maturity, roughly $184,440 in total. Under a plain ULIP, the death benefit is typically the higher of the sum assured and the fund value, which here would be $50,000. The extra protection is not free: it is priced through mortality and benefit charges, which have not been disclosed.
Worked example: Priya in Singapore
Priya, 34, earns in Singapore dollars and wants to build a dollar fund for her son’s university fees in 15 years. She chooses Wealth Plus at $5,000 a year. If she lives, she gets the fund value at maturity, which at 7% gross would be about $134,440 before charges. If she dies in year five, her family gets $50,000 at once, and the insurer keeps funding the policy, so the education fund still matures. The question she must ask is how much the cover costs each year compared with a separate dollar term plan plus a global index fund.
Zero Allocation Charges Is Only Half the Cost Story
Canara HSBC Life highlights that there are no allocation charges and no administration charges, so every dollar of premium is invested from the start. That is a meaningful improvement on older ULIP designs. But every ULIP also deducts a fund management charge from fund value and a mortality charge for life cover. Policybazaar’s GIFT City guide says Canara HSBC Life’s GIFT City plans return 100% of mortality charges at maturity, which would soften that cost, though the launch release does not say so for this plan.
Over 15 years, a 2% annual charge would cost about $21,150 compared with no charge, more than four years of premiums. Ask for the fund management charge of each fund before you choose, and compare it with a low-cost global index fund you could hold directly.
Three Dollar Plans in One Month: How They Line Up
Canara HSBC Life is not alone. Angel One notes that Ageas Federal Life launched its Aurum Advantage plan on 8 October 2026 with investments in US dollars, euros and pounds, and Bajaj Life announced Global Wealth Builder on 22 October. Earlier entrants include Tata AIA, which launched dollar life insurance for NRIs in 2024, so the category is not new, but three launches in one month is.
| Feature | Canara HSBC Global Wealth Plan | Bajaj Life Global Wealth Builder | Ageas Federal Aurum Advantage |
|---|---|---|---|
| Launch | Mid-October 2026 | 22 October 2026 | 8 October 2026 |
| Currencies | US dollar | US dollar | Dollar, euro, pound |
| Plan options | 3: Wealth, Wealth Plus, Wealth Forever | 3: Wealth, Secure, Secure Plus | Not detailed in sources |
| Fund types | Global equity, gold and silver, debt | 6 funds incl. gold, liquid, AI equity | Not detailed in sources |
| Death benefit feature | Insurer funds future premiums | Annual income of 1 premium a year | Not detailed in sources |
| Allocation and admin charges | Nil | Nil | Not detailed in sources |
| Distribution | Policybazaar | Bajaj Life IFSC office | Not detailed in sources |
Who Stands Behind the Policy
Canara HSBC Life Insurance was incorporated in 2007 and is now publicly listed. According to the launch release, Canara Bank holds 36.5%, HSBC Insurance (Asia-Pacific) Holdings 25.5% and Punjab National Bank 13%, with the remaining 25% held by public shareholders. It had 107 branch offices as of 30 September 2026 and is headquartered in Gurugram.
Some older reports quote the pre-listing split of 51%, 26% and 23%. The figures above are from the October 2026 release. Policybazaar, the distributor, says it has issued 71.6 million policies since 2008 and works with 55 insurance partners. Rishi Mathur, Chief Distribution Officer and Chief Marketing Officer at Canara HSBC Life, said “customer needs of non-resident Indians are evolving rapidly,” while Policybazaar’s Vivek Jain said NRI customers are “increasingly seeking opportunities to diversify their portfolios.”
The Currency and Tax Questions NRIs Must Answer First
A dollar policy makes most sense when your future spending will also be in dollars. Business Today, reporting Policybazaar’s July launch, noted that the rupee has lost roughly 3% a year against the dollar over three decades. If that continued, a fixed dollar expense would grow steadily in rupee terms, which is the risk a dollar savings plan removes.
On tax, Budget 2025 proposed that proceeds from life insurance issued by an IFSC Insurance Office to non-residents be exempt under Section 10(10D) without the usual premium cap, which is ₹2.5 lakh a year for domestic ULIPs, according to Taxscan. That can make GIFT City policies attractive for high-premium NRI buyers. But tax in your country of residence still applies, and returning to India changes your status. Whalesbook’s report rightly advises reading the tax implications and terms carefully.
Fact box: who regulates GIFT City insurance
Products issued from GIFT City fall under the International Financial Services Centres Authority rather than the domestic insurance regulator. Keep the policy document’s grievance and dispute-resolution clauses, and note the IFSC Insurance Office’s registration details.
Why Insurers Are Suddenly Crowding Into GIFT City
The rush has a clear trigger. Until Budget 2025, a life policy’s maturity proceeds were tax-free in India only if annual premiums stayed within caps, which made large dollar policies less appealing for wealthy NRIs. Removing that cap for IFSC policies issued to non-residents turned GIFT City into a natural home for high-premium savings products, and insurers have responded within eighteen months.
Scale is building too. Policybazaar has cited GIFT City assets under management of about $9.3 billion as of April 2026, and the government has extended IFSC tax concessions to March 2030. For an insurer, a GIFT City branch lets it collect premiums in dollars, invest in overseas markets and avoid converting money into rupees at all, which is exactly what an NRI with dollar income and dollar goals wants.
There is also a distribution logic. Policybazaar launched dollar term insurance for NRIs in July 2026 and now adds an investment-linked plan from Canara HSBC Life, so it can offer an NRI both pure protection and savings in the same currency. Canara HSBC Life, for its part, brings the reach of two public sector bank promoters and an international partner in HSBC, which is likely to matter to families who want a familiar name behind a foreign-currency policy.
What this competition means for buyers
More launches usually mean better terms. Within a month, two of the three new plans have advertised zero allocation and administration charges, which would have been unusual for ULIPs a decade ago. The next point of competition is likely to be fund management charges and the cost of the life cover itself, so buyers who wait for full brochures and compare illustrations side by side are in the strongest position. The safest approach is to treat the launch headlines as an invitation to ask questions, not as a reason to sign quickly.
Is Global Wealth Plan Right for You?
- Ask Policybazaar or Canara HSBC Life for the brochure and a benefit illustration at 4% and 8%.
- Get the fund management charge for each fund and the mortality charge for your age and cover.
- Check minimum premium, policy term and lock-in or discontinuance rules.
- Confirm tax treatment in India and in your country of residence.
- Compare the total cost with a dollar term plan plus a global fund.
Frequently Asked Questions
What is Canara HSBC Life Global Wealth Plan?
It is a US dollar, unit-linked, non-participating life insurance savings plan offered from GIFT City, aimed at NRIs and distributed through Policybazaar, with three options: Wealth, Wealth Plus and Wealth Forever.
Who can buy Canara HSBC Life Global Wealth Plan?
The launch targets non-resident Indians seeking dollar investment and protection. Detailed eligibility, including whether residents can buy, has not been published in the launch material.
What funds does Global Wealth Plan invest in?
The plan offers investment in global equities, precious metals such as gold and silver, and debt funds. Specific fund names and charges were not in the launch release.
What is the premium funding benefit in Wealth Plus?
If the life assured dies during the term, the sum assured is paid immediately and the insurer funds all future premiums, so the policy continues to maturity and the fund value is paid then.
Does Global Wealth Plan have allocation charges?
No. Canara HSBC Life says there are no allocation or administration charges. Fund management and mortality charges still apply and should be checked.
Are returns guaranteed in Canara HSBC Life Global Wealth Plan?
No. It is market-linked, so returns depend on fund performance, unless a specific benefit is expressly guaranteed in the policy.
Is a GIFT City life insurance policy tax-free for NRIs?
Budget 2025 proposed exempting proceeds of IFSC policies issued to non-residents under Section 10(10D) without the usual premium cap. Tax in your country of residence may still apply.
How is it different from Bajaj Life Global Wealth Builder?
Both are dollar ULIPs from GIFT City with no allocation or administration charges. Canara HSBC’s Wealth Plus funds future premiums after death, while Bajaj Life’s Secure Plus pays an annual income equal to one premium. Bajaj Life lists six named fund categories, including AI equities.
The Short Version
Canara HSBC Life’s Global Wealth Plan is a US dollar ULIP from GIFT City for NRIs, sold through Policybazaar. It invests in global equities, gold and silver, and debt, has no allocation or administration charges, and comes in three options. Its standout feature is Wealth Plus, where the insurer funds future premiums after the policyholder’s death so the plan still matures. Minimum premiums, fund charges and exit rules are not yet public, returns are not guaranteed, and currency and tax rules matter. Get an illustration and full charge list, and compare with Bajaj Life and Ageas Federal’s October launches.